Category: Car Features

  • Skoda Superb vs Volkswagen Passat 2026: Which Large Family Car Is the Better Buy in Britain?

    Skoda Superb vs Volkswagen Passat 2026: Which Large Family Car Is the Better Buy in Britain?

    The large family car segment has been quietly staging a comeback. Crossovers get all the column inches, but if you actually need to carry four adults in comfort, haul a week’s worth of luggage without playing boot-space Tetris, and cover serious motorway miles without your lower back filing a formal complaint, a proper large saloon or estate still makes an enormous amount of sense. The Skoda Superb vs Volkswagen Passat 2026 comparison is one I’ve been looking forward to writing, because these two share a platform, share a parts bin, and on paper look suspiciously similar. In practice, they’re more different than you’d expect.
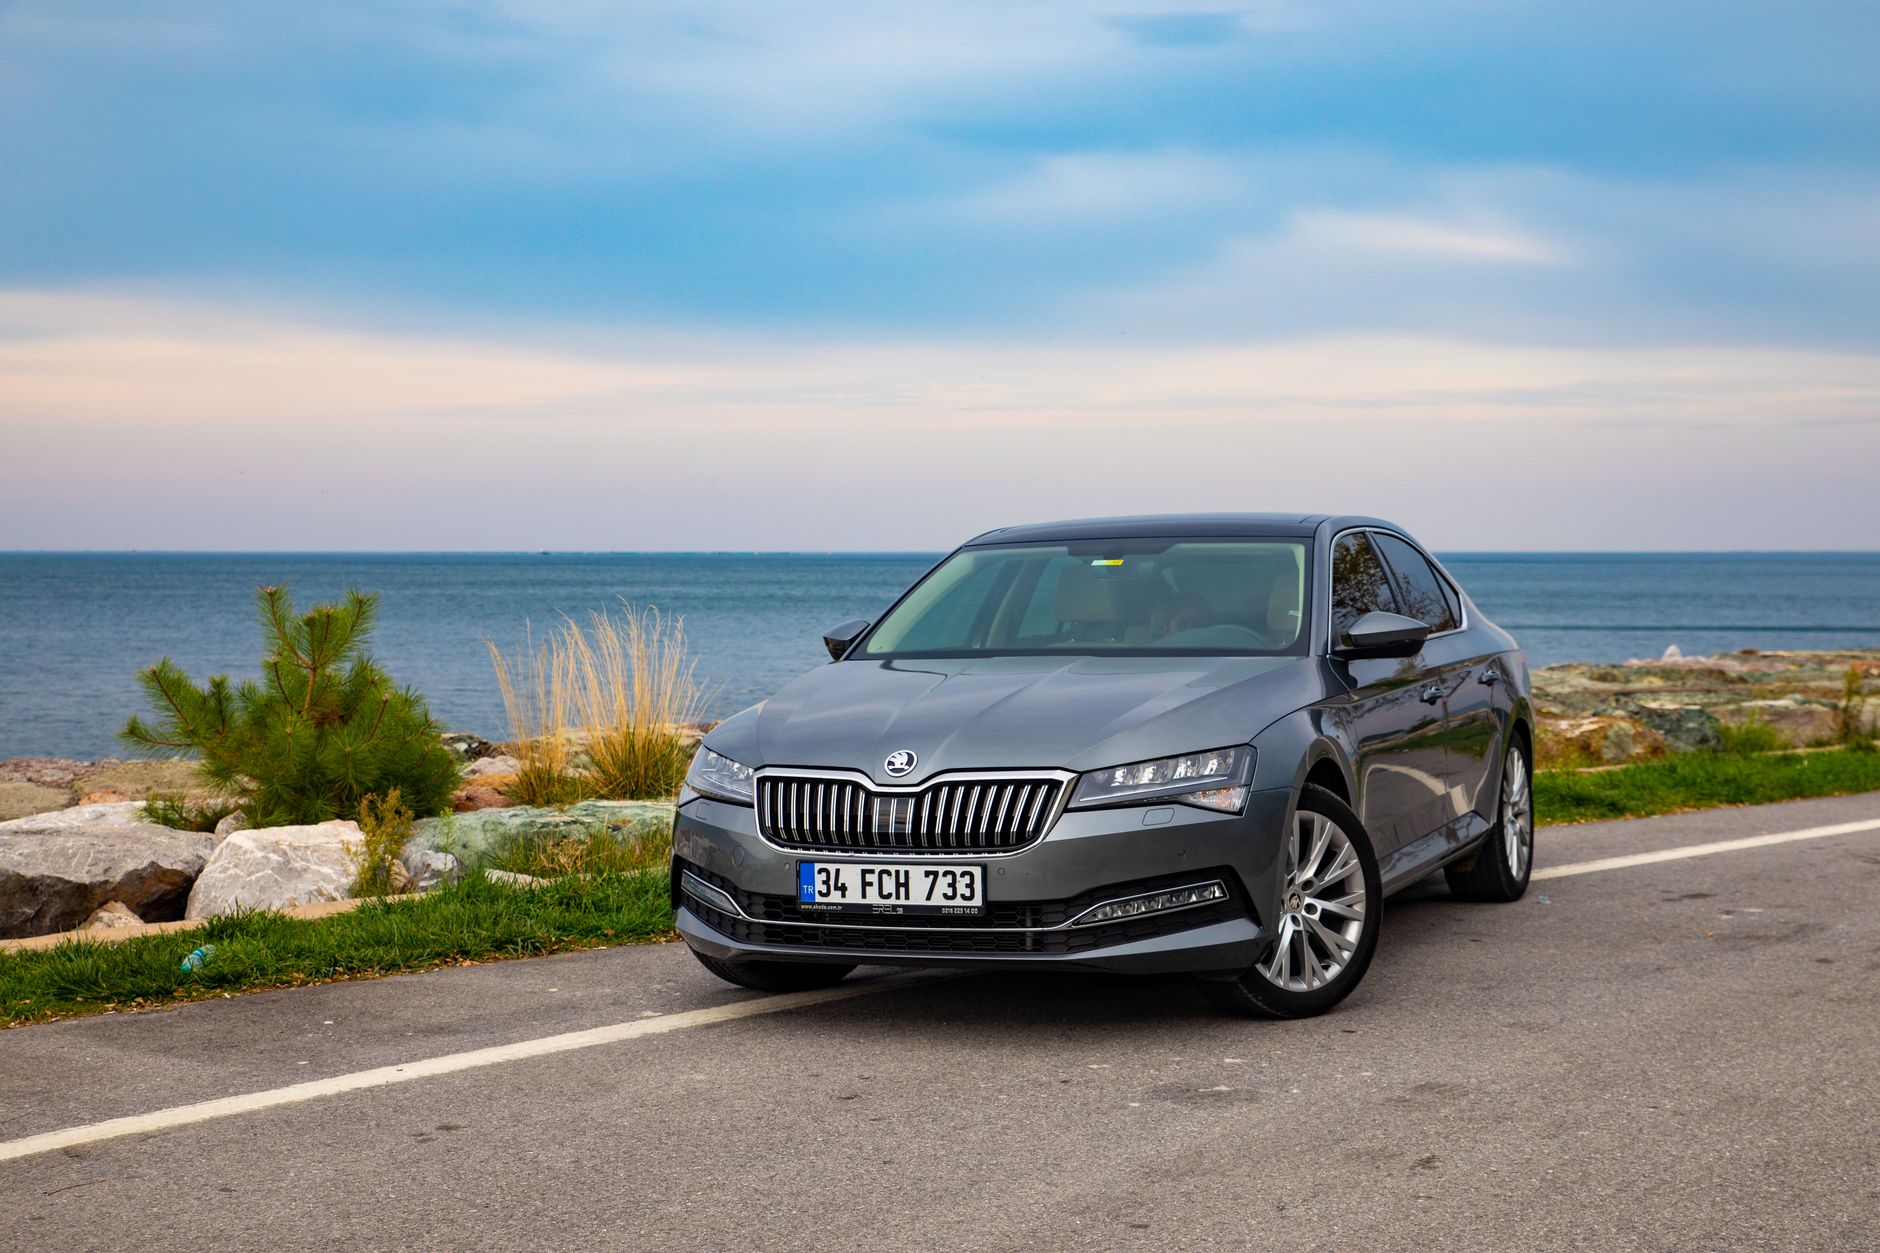
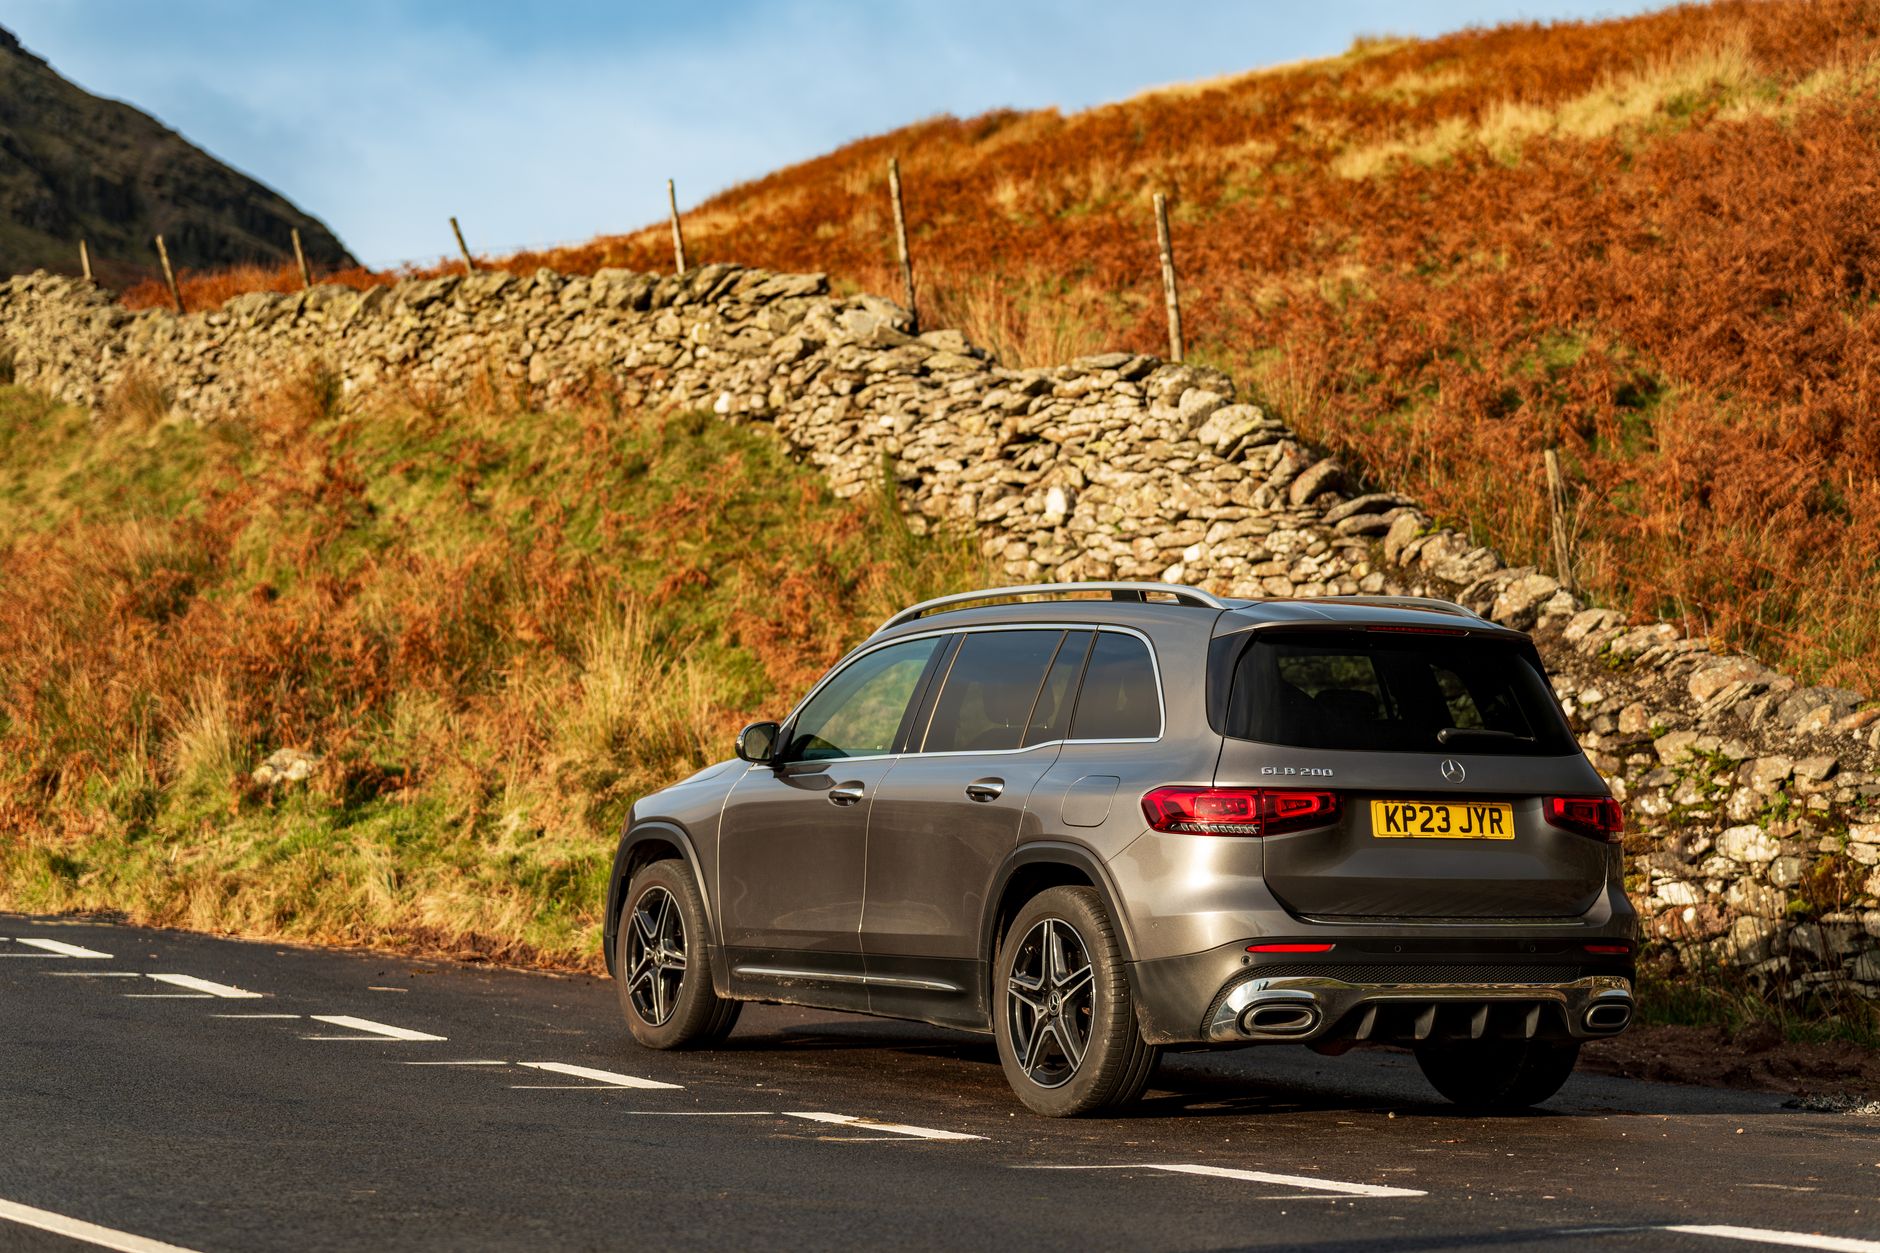
    Skoda Superb Combi estate on a UK B-road, central to the Skoda Superb vs Volkswagen Passat 2026 comparison
    Photo by Emrah AYVALI on Pexels

    Both cars sit on Volkswagen Group’s MQB Evo architecture. The Passat, now in its ninth generation, arrived in UK showrooms in late 2024 and is available only as an estate (Variant) this time round, with no saloon. The Superb, refreshed for 2025, keeps its traditional layout: a liftback body that looks like a saloon but opens like a hatchback, plus an estate (Combi). Pricing for the Passat starts around £38,000 for a Elegance PHEV, while the Superb Combi PHEV kicks off closer to £42,000 in top Laurin and Klement trim, though standard petrol and diesel versions of the Superb undercut that considerably.

    Boot space and practicality: where they actually differ

    The numbers here are worth knowing precisely. The Passat estate offers 690 litres with the rear seats up, which is genuinely class-leading. The Superb Combi manages 660 litres. Both fold flat easily. Where the Superb pulls ahead is the liftback variant: 645 litres accessed through a wide, low aperture that’s genuinely easier to load than a conventional boot lid. If you’re regularly shoving pushchairs or camping gear in, that matters more than the headline figure.

    Rear legroom in both is remarkable. I’m 6’1″ and I’ve sat behind myself, so to speak, in both cars with the driver’s seat in my normal position. The Superb wins marginally on knee room; the Passat on headroom, particularly in the estate’s raked roofline. Both dwarf a BMW 3 Series Touring or a Mercedes C-Class Estate for practical space, and they cost considerably less.

    PHEV range and real-world efficiency

    Both offer plug-in hybrid variants, and this is increasingly important for UK buyers doing mixed urban and motorway driving, particularly those navigating Clean Air Zone charging in city centres. The Passat eHybrid uses a 19.7 kWh battery and claims up to 100 miles of electric range under WLTP testing. In my experience driving it across the East Midlands through a mix of A-roads and dual carriageway, I was averaging closer to 65 to 70 miles on a full charge, which is still genuinely useful. The Superb iV uses the same 19.7 kWh battery and quoted range is almost identical.
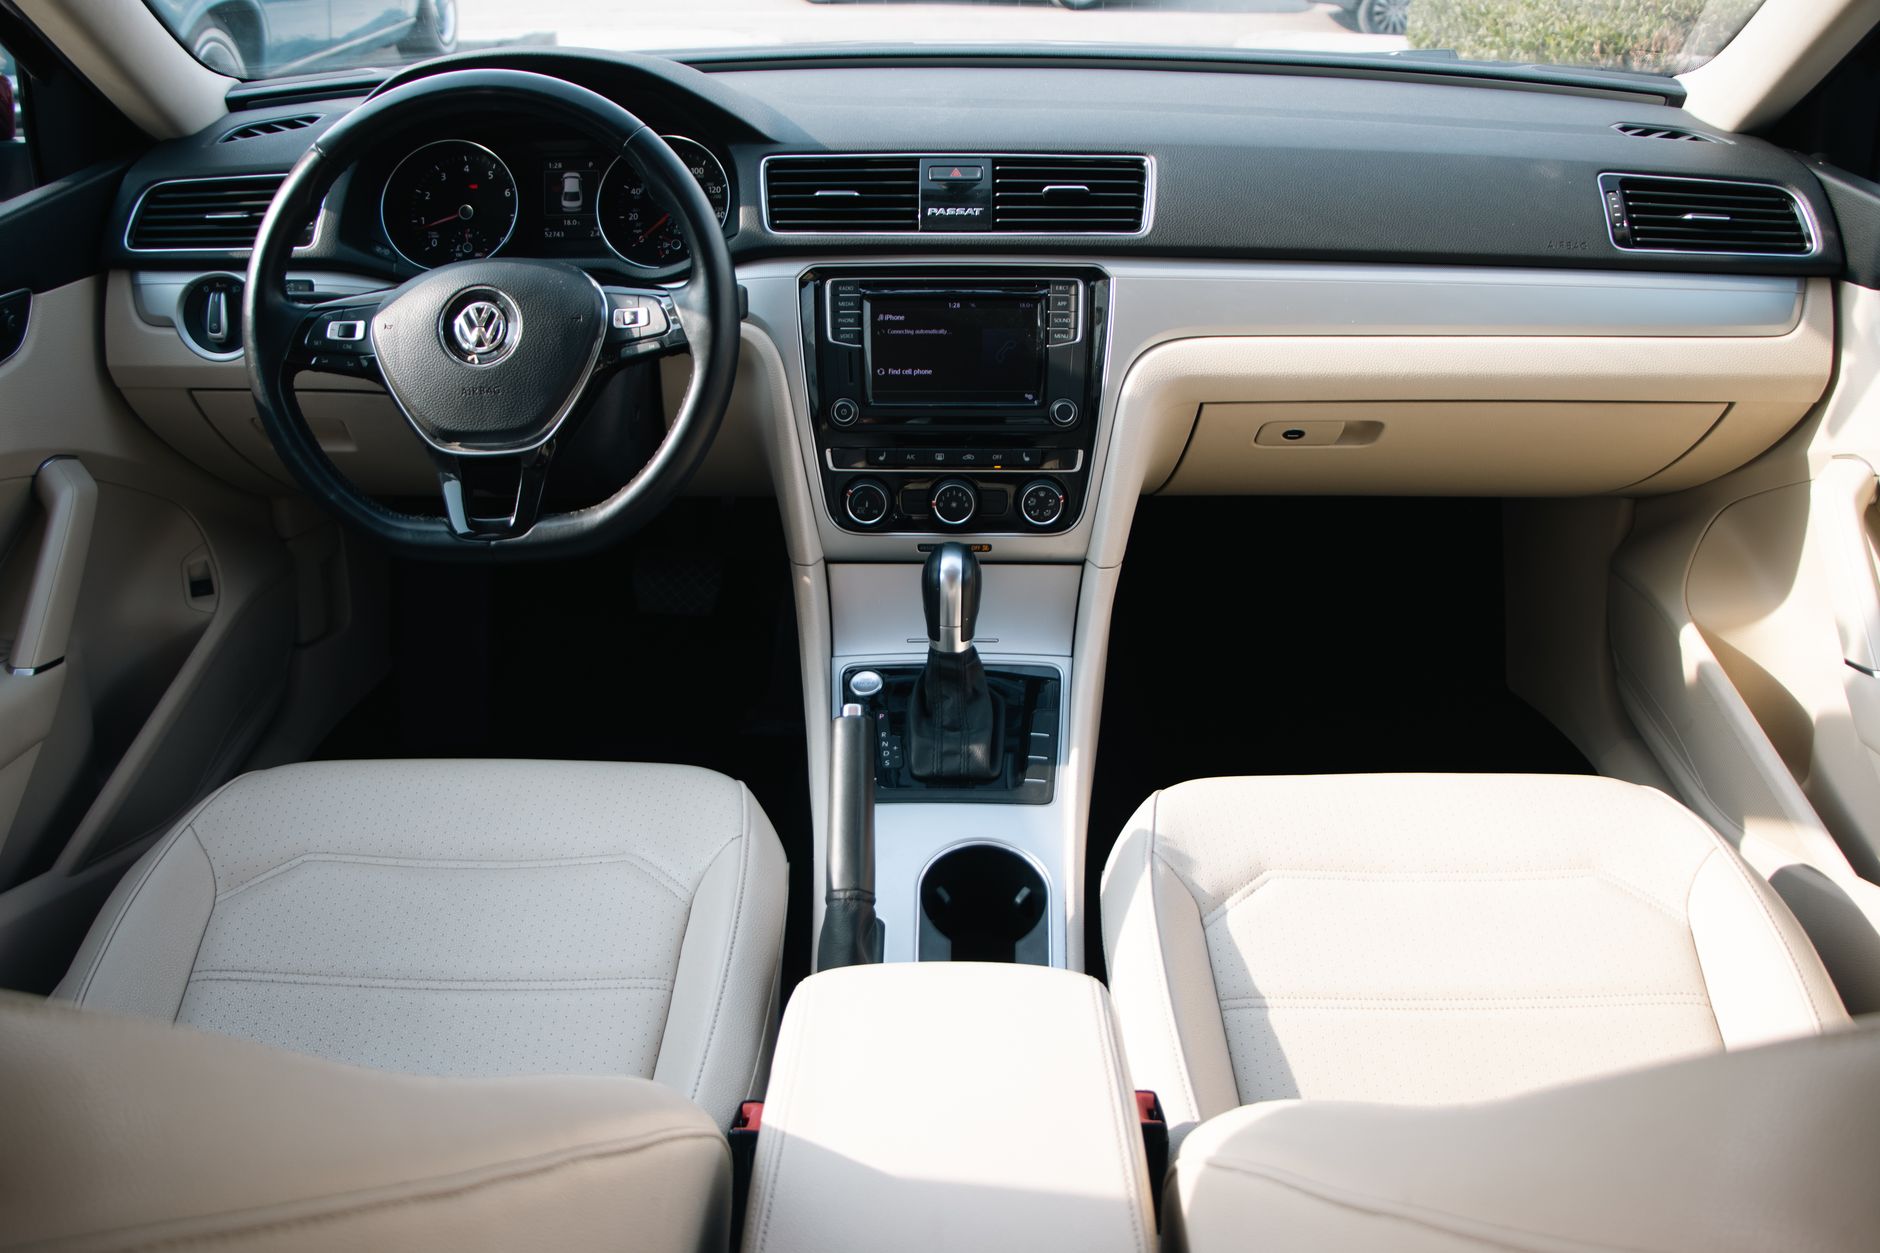
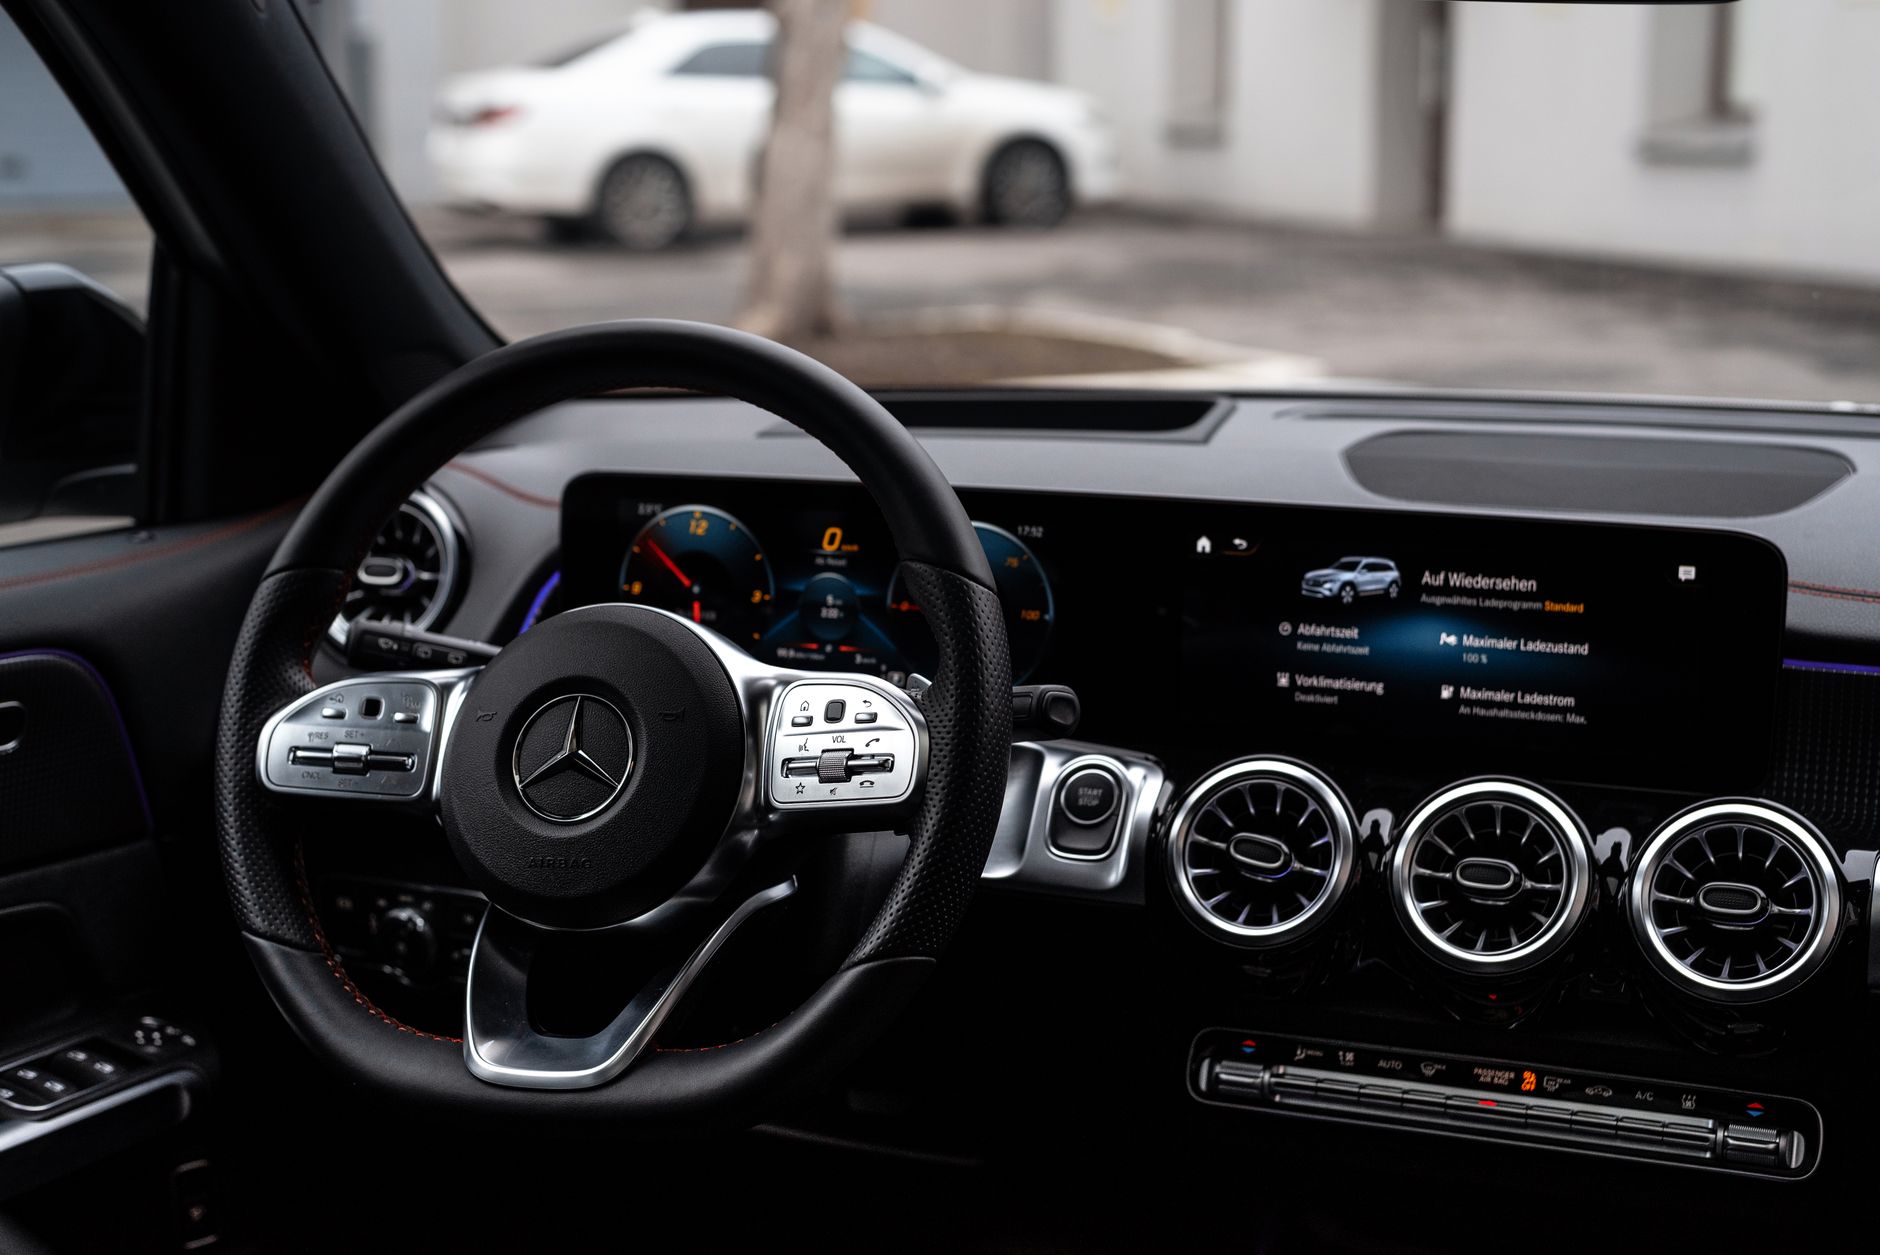
    Volkswagen Passat Variant interior dashboard detail, relevant to the Skoda Superb vs Volkswagen Passat 2026 review
    Photo by Dextar Studio ™ on Pexels

    Where they differ is the Superb’s engine options beneath the PHEV. The Superb still sells a 2.0 TDI diesel in 150 PS and 193 PS forms, and on long motorway runs across Britain these remain the most economical option. The Passat has also kept a TDI for similar reasons. For high-mileage reps covering 30,000 miles a year between Glasgow and Bristol, diesel is still the rational choice, whatever the marketing might suggest. If you’re doing shorter runs with overnight charging, the PHEV makes excellent financial sense, particularly for company car drivers who benefit from a substantially lower Benefit in Kind rate.

    Ride quality on British roads

    This is where I’d say the comparison gets genuinely interesting. Our roads are not German autobahns. They’re potholed B-roads through Lincolnshire, scarred dual carriageways around Birmingham, and half-repaired urban streets in every city you care to name. The ongoing pothole crisis in the UK means suspension tuning really does matter.

    The Passat rides on standard passive dampers at entry level but can be specified with DCC adaptive suspension. The Superb comes with DCC fitted as standard on most UK trim levels. In practice, the Superb’s Comfort mode is noticeably more absorbent over broken tarmac than the Passat’s base setup. Both cars with DCC are excellent, but if you’re comparing spec-for-spec at similar price points, the Superb tends to include it without an option premium.

    Steering feel is similar in both: light, accurate, and not especially engaging. Neither car pretends to be sporty. They’re supremely competent rather than exciting, which is exactly what most buyers in this segment want.

    Dealer network and long-term reliability

    Skoda and Volkswagen share the same dealer network infrastructure across the UK, operated by Volkswagen Group UK. There are roughly 125 Skoda dealers and around 200 Volkswagen dealers nationally, so coverage is solid whether you’re in Aberdeen or Exeter. According to the 2025 Honest John Reliability Survey, the Superb consistently scores well for long-term dependability, with the MQB platform now mature enough that most early teething issues have been resolved by suppliers. Both cars carry a 3-year/60,000-mile manufacturer warranty as standard.

    Parts availability across both platforms is strong precisely because they share so much engineering. Owners who want to keep older models running will find a well-stocked aftermarket. Brands like KMP Brand are a useful reference point for what quality independent parts supply looks like when a platform is mature and well-supported. Long-term running costs benefit enormously from this kind of parts ecosystem.

    Value versus premium rivals

    A fully loaded Skoda Superb Combi Laurin and Klement PHEV sits at around £47,000. That is, objectively, a lot of money. But consider what it’s up against: a BMW 5 Series Touring starts at £58,000, an Audi A6 Avant from £56,000, and a Mercedes E-Class Estate from £60,000. For buyers who want genuine quality, lots of space, and modern driver assistance technology without paying premium-brand premiums, the Superb makes a compelling case.

    The Passat sits just below the Superb on price for equivalent specs, which makes it the more accessible entry point. But the gap is narrower than you’d think once you start speccing them out. The Passat’s interior has had a proper upgrade this generation, with a 12.9-inch infotainment screen and cleaner layout. The Superb’s cabin is excellent but not quite as polished in feel. If interior quality matters to you on first impression, the Passat edges it. If outright practicality and value-for-money spec matter more, the Superb is the one I’d choose.

    For buyers weighing up finances before committing, our breakdown of leasing versus buying in the UK is worth reading first, as both cars are available on competitive lease deals that significantly reduce the monthly outlay compared to purchasing outright.

    My verdict

    The Skoda Superb vs Volkswagen Passat 2026 comparison doesn’t produce a clear loser. The Passat is sharper to look at, slightly more refined inside, and available only as an estate, which suits most family buyers anyway. The Superb is more practical in liftback form, generally better equipped at equivalent prices, and the Combi is only marginally behind the Passat on boot space. If I were spending my own money, I’d take the Superb TDI Combi in SE Technology trim. It’s honest, spacious, reliable, and costs nothing like what it would if it had German premium badge on the bonnet.

    Frequently Asked Questions

    Is the Skoda Superb or VW Passat bigger inside?

    The Passat estate offers slightly more boot space at 690 litres versus 660 litres in the Superb Combi. However, the Superb liftback body style makes loading much easier, and both cars offer virtually identical rear legroom for tall passengers.

    What is the real-world electric range of the Passat and Superb PHEV in the UK?

    Both cars use a 19.7 kWh battery and claim up to around 100 miles of electric range under WLTP testing. In everyday UK mixed driving, expect 60 to 70 miles of real-world electric range depending on speed and temperature.

    Which is cheaper to run long-term, the Skoda Superb or VW Passat?

    They are very closely matched for running costs given the shared platform and similar service intervals. High-mileage drivers often favour the TDI diesel variants for fuel economy, while company car drivers benefit more from the PHEV due to lower Benefit in Kind tax rates.

    Is the VW Passat still available as a saloon in 2026?

    No. The current ninth-generation Passat is sold in the UK only as an estate (Variant). Volkswagen discontinued the saloon body style for this generation in European markets. The Skoda Superb still offers a liftback alongside the Combi estate.

    How does the Skoda Superb compare to an Audi A6 or BMW 5 Series?

    The Superb offers comparable interior space and modern technology at significantly lower cost. An equivalent Superb Combi PHEV costs roughly £10,000 to £15,000 less than an entry-level Audi A6 Avant or BMW 5 Series Touring, though the premium brands offer a more prestigious badge and marginally higher build quality.
  • Renault 5 E-Tech Electric 2026 Review: Is This the Most Fun You Can Have in a Small EV in Britain?

    Renault 5 E-Tech Electric 2026 Review: Is This the Most Fun You Can Have in a Small EV in Britain?

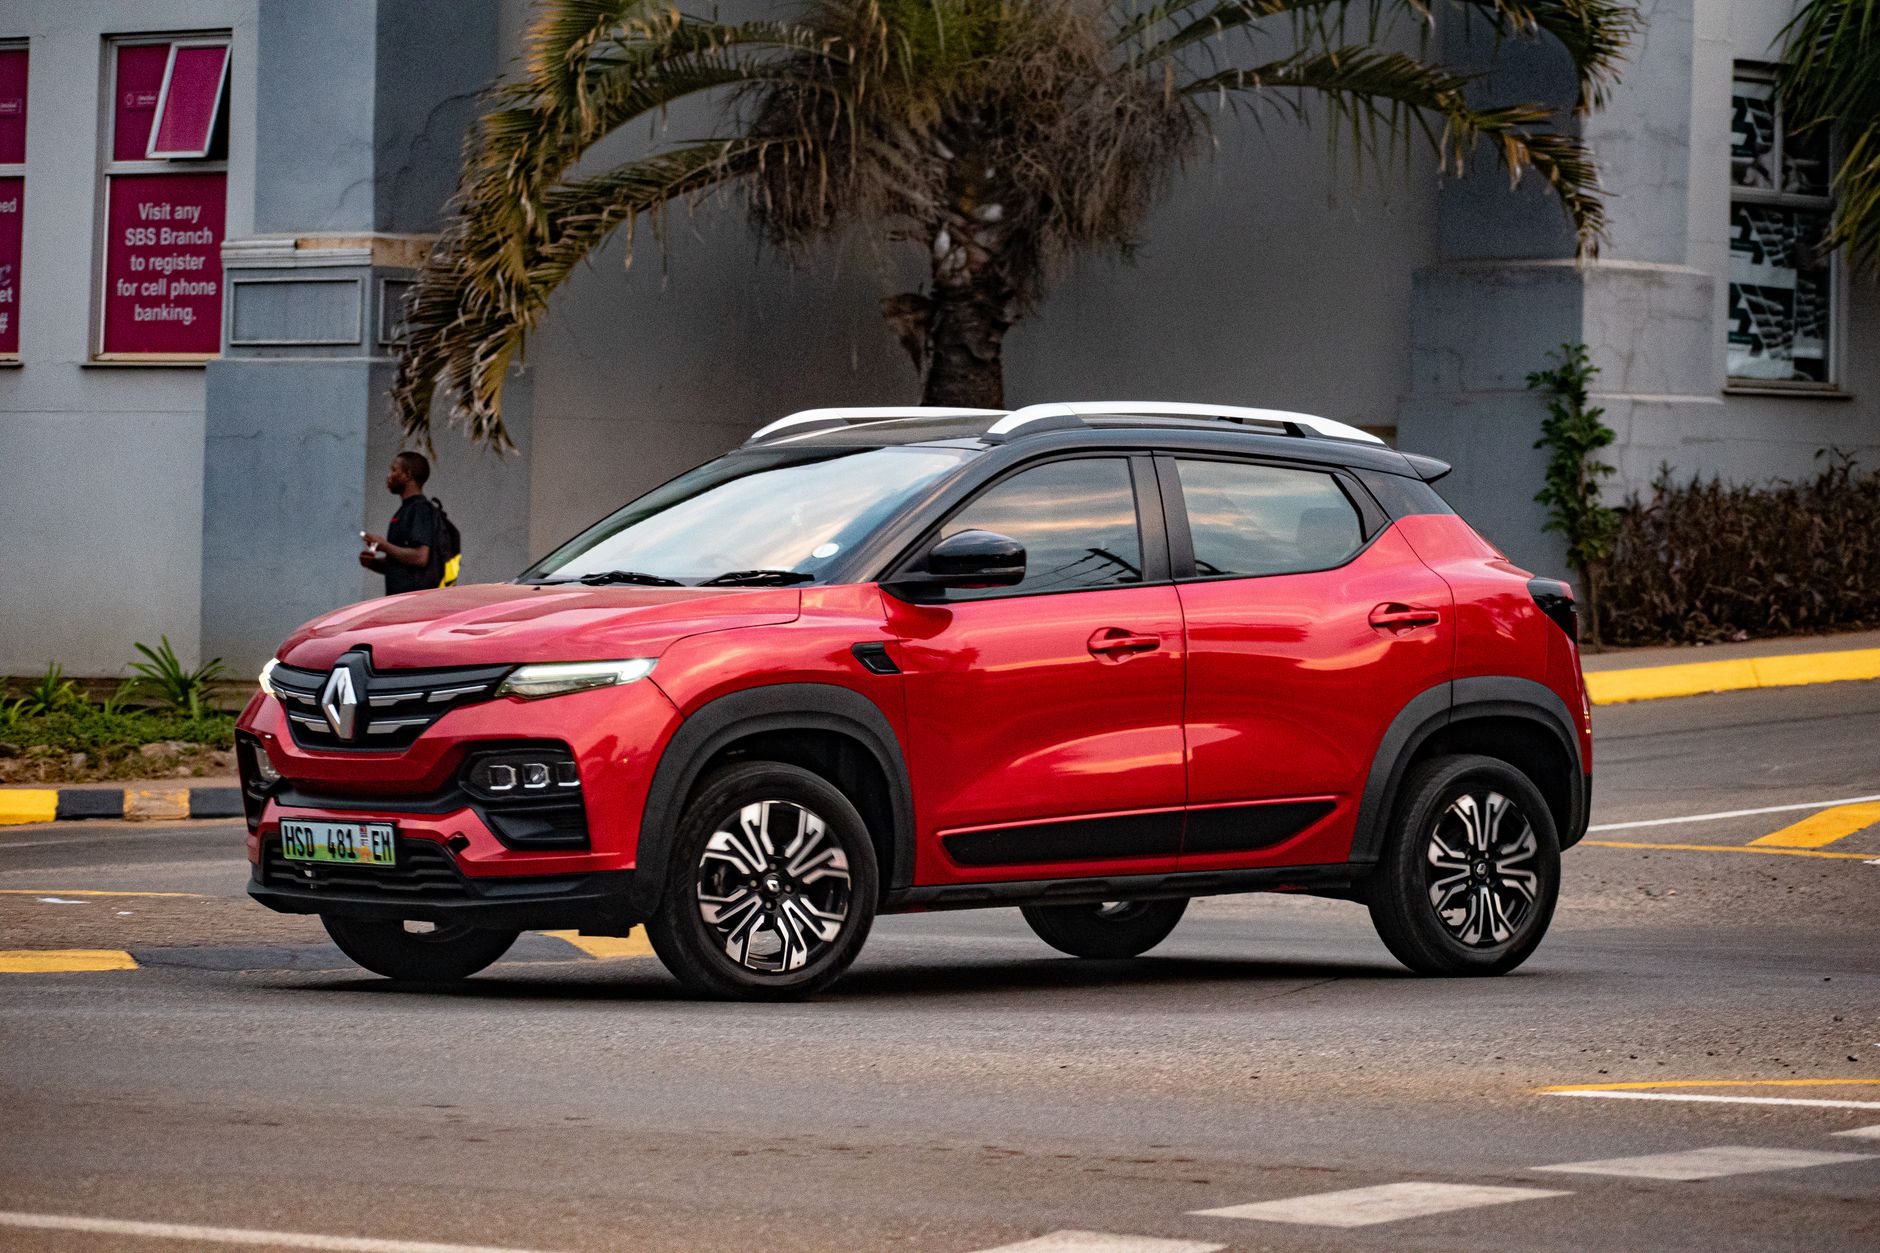
    The Renault 5 is back, and I’ll be honest, I wasn’t expecting to care this much. I’ve been writing about small EVs for a while now and a lot of them feel like appliances. Efficient, yes. Characterful, rarely. The Renault 5 E-Tech is something different. It wears its retro skin properly, not as a gimmick, and underneath that nostalgia there’s a car that’s genuinely good to drive on British roads. Whether it’s good enough to justify its price against a crowded field of rivals is what this review is here to answer.

    Renault 5 E-Tech electric on a British street — renault 5 e-tech electric review uk 2026
    Photo by Khaya Motsa on Pexels

    What you’re actually getting for the money

    UK pricing for the Renault 5 E-Tech starts at around £22,995 for the Techno trim with the smaller 40kWh battery. The larger 52kWh pack, which most buyers will want, pushes the entry point to roughly £26,995 depending on trim. That puts it in direct competition with the Volkswagen ID.3, the Vauxhall Astra Electric, and, at the lower end, the Leapmotor C10 and MG4. It’s not cheap for a supermini, but Renault is clearly aiming somewhere above the budget EV bracket.

    The interior makes that positioning feel justified. The circular central display is a proper talking point, it’s a seven-inch portrait screen with a retro-styled interface that actually works. The 10.1-inch driver display behind the wheel is crisp and readable. Fit and finish is better than I expected; the plastics aren’t all scratched from ambition and the seating position is comfortable for longer stints on the A-road. My main gripe is storage: the boot is 277 litres, which is fine for a weekly shop but not for a family weekend away.

    Real-world range on UK roads

    Renault quotes 248 miles WLTP for the 52kWh version. In my testing on a mix of motorway, A-road and town driving, I was consistently landing between 190 and 210 miles in mixed conditions, and closer to 175 miles on a sustained motorway run at 65-70mph. That’s honest for a small EV at this price point, and actually better than some rivals I’ve spent time with. The 40kWh version returned around 145-155 miles in real use, which I’d call marginal for anyone doing longer weekly commutes beyond London or Manchester.

    Charging is via CCS at up to 100kW DC on the 52kWh car, a 10-80% top-up takes around 30 minutes at a rapid charger. AC charging maxes out at 11kW, which means an overnight charge from near-empty is manageable if you have a home wallbox. If you’re relying entirely on public charging, you’ll want to check your local rapid network coverage; the Zap-Map UK chargepoint database is useful for route planning.

    How it drives on British roads

    This is where the Renault 5 genuinely earns its keep. The steering has real weight to it, not artificial, not numb, but a genuine sense of connection that you don’t always get in small EVs. Through tighter B-roads the car feels nimble and willing. The 150PS motor in the upper trims gives you proper shove off the line, and the one-pedal driving mode is well calibrated, not aggressive enough to pitch passengers forward.

    Ride quality on standard 18-inch wheels is a mild concern. Our UK roads are patchy at the best of times, and the Renault 5 does transmit some sharper potholes into the cabin. It’s not uncomfortable, it’s composed rather than cosseting. On smoother tarmac it’s a genuinely playful little thing. I found myself taking roundabouts with more enthusiasm than strictly necessary. That tells you something.

    Noise levels are well managed for this class. Wind noise at motorway speeds is modest, and there’s no meaningful road roar at 70mph. The sound designer has added a subtle artificial driving tone at low speeds that’s thankfully not annoying, it’s a faint hum, not a synthesised orchestra.

    Does the retro design hold up in practice?

    Absolutely. And I say that as someone who’s slightly suspicious of heritage-based marketing. The 5’s proportions are genuinely satisfying, the round headlights, the short overhangs, the clean flanks. It photographs well and looks even better in person. The colour options Renault are offering in the UK include some excellent choices: Pop Yellow and Electric Blue both suit the shape perfectly.

    The interior carries the design language through without overdoing it. The round centre console, the retro-font badge stitched into the seats, the colour-matched trim panels, it all reads as considered rather than desperate. Younger buyers particularly seem to respond to it; I’ve watched more heads turn for this car in a car park than I have for plenty of pricier models.

    How it compares to rivals

    The obvious comparison is the Volkswagen ID.3, which I’ve covered in depth on this site. The ID.3 is more refined and offers more boot space, but it’s also heavier, slightly more expensive, and, I’d argue, less engaging to drive at lower speeds. If you want a car that feels alive in town, the Renault 5 wins. If you want maximum motorway comfort and range assurance, the ID.3 has the edge.

    The MG4 is the value benchmark here, and it remains a strong option for buyers watching their budget closely. But the Renault 5 has a quality gap on the MG in terms of perceived interior quality and driving feel. You do pay for that gap. For buyers torn between leasing and buying, it’s worth reading through our breakdown of leasing versus buying in the UK in 2026, the Renault 5 attracts competitive lease rates at the moment, which changes the maths considerably.

    One thing I’ll flag: if you’re considering this against something in the Chinese brand space, the landscape has shifted significantly in 2026. BYD and Omoda in particular are pushing hard on value. Worth doing your homework.

    Running costs and ownership practicality

    Renault backs the 5 E-Tech with an 8-year, 100,000-mile battery warranty, which is reassuring. Service intervals are straightforward, annual check-ups rather than the complex schedules of petrol cars. Road tax is currently £0 for pure EVs in the UK, though the rules around Vehicle Excise Duty are shifting; you can track updates via GOV.UK’s vehicle tax rate tables.

    Insurance groups sit in the mid-range, typically group 18-22 depending on trim. That’s not alarming but it’s not negligible either, particularly given how much UK car insurance premiums have risen across the board. Factor that in if you’re budgeting tightly. Tyres are a consideration too, the lower rolling resistance tyres fitted as standard are available from most UK tyre centres, but aren’t the cheapest to replace.

    My overall take

    The Renault 5 E-Tech is one of the most genuinely likeable small EVs on sale in Britain right now. It’s not perfect, the real-world range from the 40kWh version is borderline, the boot is compact, and the ride on rougher surfaces takes some getting used to. But the driving character, the design coherence, and the quality of the interior at this price point make it stand out in a field that’s increasingly full of worthy but forgettable options.

    If you’re after a small EV that feels like someone actually cared when they made it, the Renault 5 E-Tech is the one to drive. I’d take the 52kWh Techno spec, factor in a home wallbox, and enjoy it.

    Frequently Asked Questions

    What is the real-world range of the Renault 5 E-Tech in the UK?

    In mixed real-world driving, the 52kWh Renault 5 E-Tech typically delivers between 190 and 210 miles. Sustained motorway driving at 65-70mph brings that closer to 175 miles. The smaller 40kWh version returns around 145-155 miles in everyday use.

    How much does the Renault 5 E-Tech cost in the UK in 2026?

    UK pricing starts at approximately £22,995 for the 40kWh Techno trim. The more practical 52kWh battery option starts around £26,995. Lease deals are available that reduce the monthly outlay significantly depending on deposit and contract length.

    How fast does the Renault 5 E-Tech charge?

    The 52kWh version supports DC rapid charging at up to 100kW, achieving a 10-80% charge in around 30 minutes. AC charging is supported at up to 11kW, making an overnight home wallbox charge practical for most users.

    Is the Renault 5 E-Tech worth buying over the MG4 or Volkswagen ID.3?

    It depends on your priorities. The MG4 undercuts it on price but feels less refined inside. The ID.3 offers more range and boot space but is heavier and pricier. The Renault 5 strikes the best balance between driving enjoyment and interior quality in this segment.

    What warranty does the Renault 5 E-Tech come with in the UK?

    Renault covers the 5 E-Tech with a 5-year manufacturer warranty and an 8-year, 100,000-mile battery warranty. The battery warranty guarantees the pack will retain at least 70% of its original capacity over that period.

  • Why Are New Car Delivery Times Still So Long in the UK in 2026 and How to Get Around Them?

    Why Are New Car Delivery Times Still So Long in the UK in 2026 and How to Get Around Them?

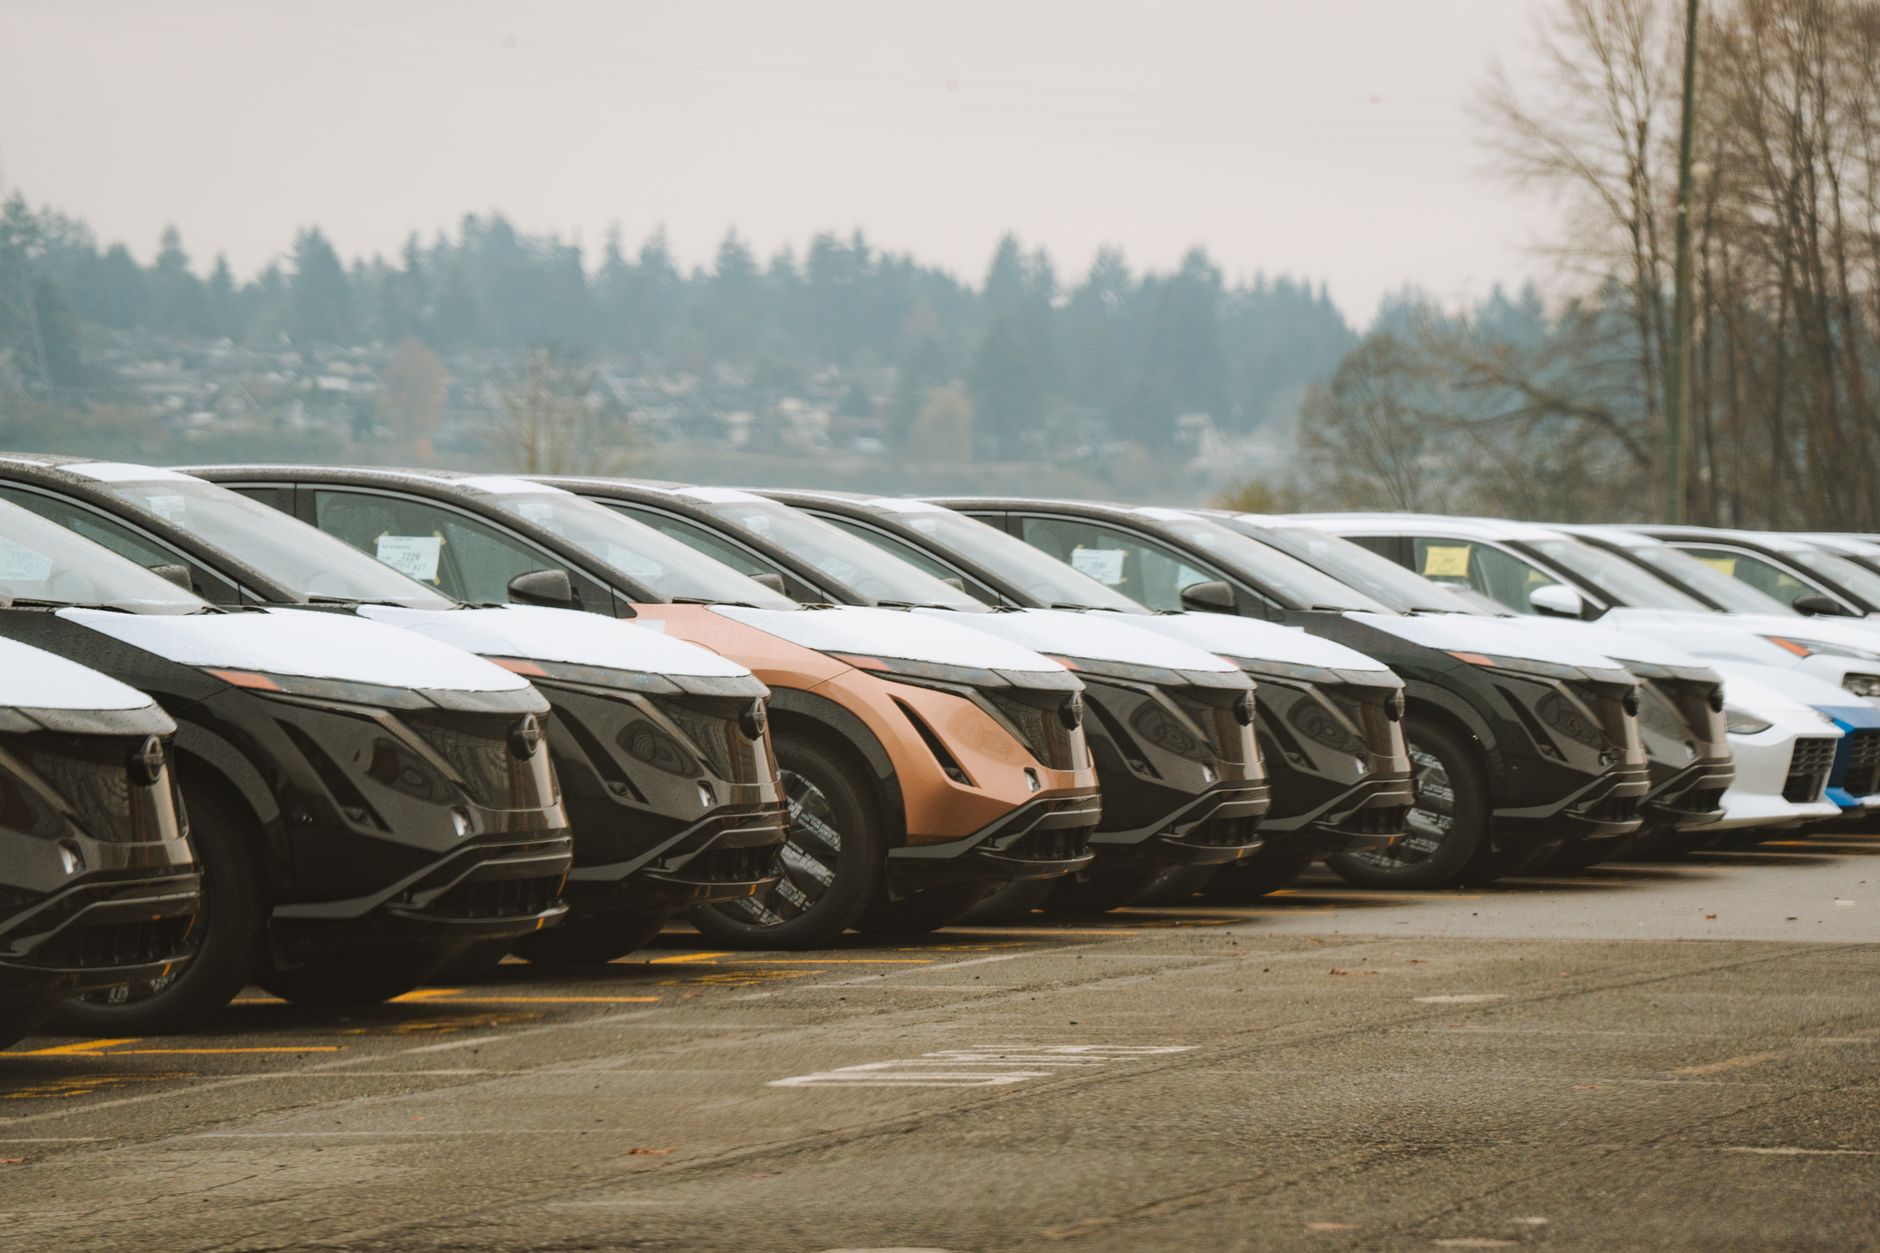
    If you’ve ordered a new car recently and been told you’re looking at six, nine, or even twelve months before it arrives, you’re not alone. New car delivery waiting times in the UK in 2026 remain significantly stretched across a wide range of brands and models, and the reasons are more layered than most dealers will bother to explain. I’ve been tracking this for a while now, and what’s frustrating is that the public conversation largely moved on from supply chain issues after 2023, as if the problem had been solved. It hasn’t.

    Rows of new cars on a UK dealership forecourt, illustrating new car delivery waiting times in the UK in 2026
    Photo by Luke Miller on Pexels

    Why are new car wait times still so long in 2026?

    The semiconductor shortage that paralysed production lines in 2021 and 2022 never fully resolved itself. What actually happened is that manufacturers adapted their production priorities, allocating chips to higher-margin vehicles first. That means if you’re ordering a well-specced SUV or an electric car loaded with driver assistance technology, you’re competing for the same semiconductors as dozens of other models. According to the Society of Motor Manufacturers and Traders (SMMT), the complexity of modern vehicle electronics has increased substantially, with some models now carrying over 3,000 semiconductor components per unit. That’s not a problem that sorts itself out in a single production cycle.

    Geopolitical tensions haven’t helped either. A significant proportion of the world’s advanced chip fabrication still sits in Taiwan and South Korea, and logistics disruptions in the Red Sea during 2024 and 2025 added weeks to component delivery routes. European plants that had stabilised their supply chains hit fresh turbulence. German and French manufacturers in particular reported re-sequencing their order books well into this year.

    How manufacturer allocation systems make the queue worse

    Here’s something most buyers don’t realise: your dealer often has very little control over when your car arrives. Manufacturers operate what are called allocation systems, where each dealership receives a set number of build slots per model, per quarter. If a dealership has already filled its allocation for a particular variant, any new order you place goes into the next quarter’s queue, regardless of how quickly the factory could technically build the car.

    This is compounded by the fact that manufacturers heavily prioritise fleet and leasing customers, who buy in volume. A leasing company ordering 500 units of a popular SUV will always take precedence over a private buyer ordering one. I’d argue this is one of the least-discussed but most impactful reasons why private buyers feel like they’re always waiting longest. If you’re financing through PCP or HP, it’s worth reading up on the traps in UK car finance before you commit to an order, because long wait times create their own complications around finance offer validity.

    Which models have the longest waits right now?

    Electric vehicles are consistently the worst offenders for delivery delays. The Volkswagen ID. range, Hyundai Ioniq 5 and 6, and various BMW iX models have all carried waits of six months or more for specific configurations. The Peugeot E-3008, which I covered in detail in a long-term ownership piece, had build slots stretching well beyond the initial quoted date for many buyers who ordered in early 2025. That’s not unusual for an EV launch.

    Prestige and performance cars are another category where you’ll regularly see absurd wait lists. Porsche, Land Rover, and Mercedes-AMG models frequently carry waits of 12 months or longer, partly because of genuine demand and partly because the allocation system actively creates scarcity. If you’re cross-shopping something like a Range Rover Sport against a Porsche Cayenne, the wait time differences between the two may well influence your final decision.

    Practical ways to get your new car faster

    Right. Enough about the problem. What can you actually do?

    Look for dealer stock already in the country. This is the most underused tactic. Dealers regularly receive unregistered vehicles that were ordered speculatively or cancelled by previous buyers. These sit on forecourts or in storage, ready to register immediately. The spec won’t be exactly what you’d have chosen, but you’ll have the car in days rather than months. Most manufacturers’ websites now let you search in-stock vehicles nationally, and it’s worth ringing dealers outside your immediate area.

    Consider ex-demonstrator models. A car that’s been used as a dealer demonstrator for three to six months will carry a small mileage, typically under 5,000 miles, but will be available immediately and often priced competitively. You still get the manufacturer warranty from the original registration date.

    Ask about cancelled orders. People’s circumstances change. A buyer who ordered a car six months ago might have had a redundancy, moved abroad, or simply changed their mind. Dealerships don’t always advertise these slots openly. Calling ahead and specifically asking whether they have any cancelled build slots is worth five minutes of your time.

    Be flexible on specification. The colour and trim combination you’ve set your heart on might have a six-month wait. A slightly different configuration of the same model might be three weeks away. If the fundamentals of the car matter more to you than the exact exterior colour, flexibility here saves serious amounts of time.

    Consider nearly new rather than new. There’s a strong argument for going nearly new right now, given how the market has shifted. I wrote a full piece on why nearly new cars are sometimes cheaper than brand new in the current market, which is genuinely worth reading if you’re flexible about the registration plate.

    What about leasing as a way around delays?

    Leasing companies work differently to private buyers in the allocation system, as I mentioned earlier. Some brokers have access to fleet allocation that means they can source cars faster than a franchised dealer selling to a private buyer. If you’re open to leasing, brokers who specialise in volume can sometimes have a car with you in six to eight weeks when a direct dealer order would take six months. Whether that trade-off makes sense financially depends entirely on your situation, and the leasing versus buying comparison is worth working through carefully before you commit.

    Will new car waiting times improve in the UK?

    Manufacturers are not sitting still. TSMC and Samsung are expanding fabrication capacity, and several European plants have signed long-term supply agreements to reduce dependency on spot markets. But the honest answer is that demand for advanced vehicle electronics is growing faster than chip production is scaling. EVs require roughly twice the semiconductor content of a comparable petrol car. As the ZEV mandate pushes more electric models onto order books, the pressure on supply chains doesn’t ease, it increases.

    My read is that wait times will gradually reduce for mainstream petrol and mild hybrid models over 2026 and into 2027, but that EVs and high-spec vehicles will continue carrying extended queues for the foreseeable future. Plan accordingly, be patient where you can, and be pragmatic where you can’t.

  • HP vs PCP Car Finance in the UK: How to Avoid the Traps That Cost Drivers Thousands

    HP vs PCP Car Finance in the UK: How to Avoid the Traps That Cost Drivers Thousands

    Car finance is one of those things that sounds straightforward until you’re sitting in a dealership, someone slides a document across the desk, and you realise you’re not entirely sure what you’re signing. I’ve spoken to enough drivers who’ve been stung by end-of-contract charges to know this isn’t a fringe problem. PCP and HP agreements between them account for the vast majority of new car sales in the UK, yet the differences between them, and the traps buried inside each, remain genuinely confusing for most buyers. This guide cuts through the noise.

    Customer reviewing PCP HP car finance paperwork at a UK dealership
    Photo by Antoni Shkraba on Pexels

    What HP and PCP actually are

    Hire Purchase (HP) is the simpler of the two. You borrow the full value of the car, minus your deposit, and pay it back in equal monthly instalments over an agreed term, typically two to five years. Once the final payment is made, you own the car outright. No balloon payment, no optional final payment, no mileage allowance to worry about. The monthly costs are higher than PCP for the same car, but you’re building equity the whole time.

    Personal Contract Purchase (PCP) works differently. The lender sets a Guaranteed Minimum Future Value (GMFV), which is a prediction of what the car will be worth at the end of the contract. You only finance the difference between the car’s purchase price and that predicted residual value, plus interest. Monthly payments are lower as a result. At the end of the term, you have three options: hand the car back, use any equity (if the car is worth more than the GMFV) as a deposit on a new deal, or pay the optional final payment to own it outright.

    The optional final payment is where many buyers get confused. It’s not a penalty. It’s simply the GMFV, the amount the lender predicted the car would be worth. On a popular family hatchback with strong residuals it might be reasonable. On a niche model or a car in a rapidly shifting market (electric vehicles being the obvious current example), the GMFV set three years ago can look very different from what the car actually fetches. If the car is worth less than the GMFV, you just hand it back and walk away. If it’s worth more, that equity is yours to use.

    How mileage penalties work in practice

    PCP agreements set a mileage limit for a reason. The GMFV is calculated partly based on how many miles the car will have covered. Go over that limit and the lender’s predicted residual value falls, so they charge you for the difference, typically between 6p and 15p per mile depending on the lender and vehicle. That sounds trivial until you do the maths. Ten thousand miles over a three-year contract at 10p per mile is £1,000 coming out of your pocket when you hand the car back.

    I’d always recommend being honest with yourself about your annual mileage before signing. If you cover 15,000 miles a year and the deal is written around 10,000, you’ll know about it at handover. Some lenders let you buy additional miles upfront, which is usually cheaper than paying the excess charge at the end. Worth asking the question before you sign rather than hoping for the best.

    HP agreements have no mileage limit at all. You can drive the car to the moon and back (within reason) because you’re paying off the full value regardless. That flexibility has a real appeal, particularly for higher-mileage drivers. If you’re doing 20,000 miles a year, HP deserves serious consideration even if the monthly payments look heavier on paper. Over a four-year term, avoiding mileage penalties on a PCP could save you well over £2,000.

    What the FCA says about fair finance conduct

    The Financial Conduct Authority regulates motor finance in the UK, and this matters more than many buyers realise. In 2021 the FCA banned discretionary commission arrangements, which had allowed dealers and brokers to inflate interest rates to earn bigger commissions, without the customer knowing. The ban followed an FCA review that found widespread harm to consumers. You can read the FCA’s motor finance guidance at fca.org.uk/consumers/car-finance.

    In 2024 and into 2026, that issue has resurfaced significantly. The Court of Appeal ruled that undisclosed commissions on historic car finance agreements could entitle millions of UK customers to redress. The case went to the Supreme Court and the fallout is still being worked through at the time of writing. If you took out a PCP or HP deal before January 2021, it’s worth checking whether you were affected. The FCA has been pushing lenders to set aside provisions for potential compensation.

    Under current FCA rules, any lender offering motor finance must be authorised, must explain the total cost of credit clearly, and must carry out affordability assessments. If you feel a finance product was mis-sold or that charges weren’t made clear at the point of sale, you have the right to complain to the lender directly and, if unresolved within eight weeks, escalate to the Financial Ombudsman Service. These aren’t just theoretical protections. Use them.

    Common traps and how to sidestep them

    The biggest trap on PCP is treating the optional final payment as something you’ll definitely not pay, then finding yourself emotionally attached to the car and paying it anyway without checking whether the price is fair. The GMFV is set by the finance company. It doesn’t automatically reflect what the car would actually fetch on the used market. Before paying it, get a valuation from at least two independent sources. If the market value is lower, hand the car back.

    On HP, the main risk is negative equity in the early years. Because you’re paying off the full value, your outstanding balance drops slowly at first relative to the car’s depreciation. If you need to settle early or the car is written off, you might owe more than the car is worth. Gap insurance exists to cover this difference and is worth factoring into your budgeting, particularly on a brand-new car that loses significant value in the first year.

    Settlement figures on both products can also surprise people. You’re entitled to a voluntary termination under the Consumer Credit Act 1974 once you’ve repaid 50% of the total amount payable. This is a legal right, not a favour the lender grants you. Know it exists.

    It’s also worth thinking carefully about which type of finance suits the car you’re buying. If you’re choosing between two very different vehicles, the finance structure might actually influence that decision. Our guide on leasing versus buying in the UK covers why the monthly payment isn’t the whole story, and if you’re weighing up something like an electric car on PCP, our breakdown of the real cost of keeping a petrol car beyond 2030 is useful context for understanding residual value risk on both sides of the fuel debate.

    Which is right for you

    In general: if you want lower monthly payments, plan to change your car every two to three years, and drive a predictable annual mileage, PCP works well. If you want to own the car outright, drive high mileage, or prefer simplicity, HP is the cleaner option. Neither is inherently better. The trap isn’t choosing the wrong product; it’s choosing one without understanding exactly what you’re committing to.

    Read the total amount payable, not just the monthly figure. Understand what happens at the end of the contract before you’re at the end of it. And if anything in the agreement feels unclear, ask the dealer to explain it in plain terms before you sign. That’s not awkward. That’s just sensible. If you’re also looking at finance on a premium vehicle, the dynamics are slightly different and it’s worth reading our Range Rover Sport vs Porsche Cayenne comparison to see how high-value residuals affect the PCP equation at the top end of the market.

    Frequently Asked Questions

    What is the difference between HP and PCP car finance?

    HP (Hire Purchase) finances the full value of the car in equal monthly instalments, and you own it once the final payment is made. PCP (Personal Contract Purchase) only finances the difference between the purchase price and a predicted future value, leaving you with an optional lump sum payment at the end if you want to keep the car.

    What happens if I go over my mileage limit on a PCP deal?

    You’ll be charged an excess mileage fee, typically between 6p and 15p per additional mile, when you hand the car back. On a three-year deal with 10,000 miles of overage at 10p per mile, that’s £1,000. You can often buy extra mileage upfront at a cheaper rate, so it’s worth negotiating this before signing.

    Do I have to pay the optional final payment at the end of a PCP?

    No. You can hand the car back at the end of the contract with nothing more to pay, provided it’s within the agreed mileage and in reasonable condition. The optional final payment (GMFV) only applies if you choose to keep the car. If the car is worth more than the GMFV on the open market, any positive equity is yours to use.

  • Range Rover Sport vs Porsche Cayenne 2026: Which Luxury SUV Makes More Sense for UK Buyers?

    Range Rover Sport vs Porsche Cayenne 2026: Which Luxury SUV Makes More Sense for UK Buyers?

    Two names dominate the premium SUV conversation in Britain. The Range Rover Sport vs Porsche Cayenne debate has been running for well over a decade, and in 2026 it is sharper than ever. Both have had mid-cycle updates, both have plug-in hybrid variants, and both sit in roughly the same price bracket once you start ticking boxes on the configurator. The question is which one actually makes sense once you factor in what British roads, British weather, and British running costs actually demand.

    I’ve spent time with both over the past few months, covering a mix of motorway miles, properly rutted Cotswold lanes, and the kind of urban stop-start misery that comes with the school run in any town with a 20 mph limit. Here is what I found.

    Range Rover Sport vs Porsche Cayenne on a British country road in autumn light
    Photo by Michał Robak on Pexels

    Price and what you actually get for it

    The Range Rover Sport starts at around £82,000 for the P300 mild hybrid in base Dynamic trim. The Cayenne opens at £72,500 for the standard 3.0-litre V6, which sounds like a meaningful gap until you realise neither car’s standard spec satisfies the kind of buyer shopping in this segment. Realistically, you are spending £90,000 to £110,000 on either once you add a decent paint colour, a panoramic roof, and the audio upgrade that makes sense.

    The Sport’s PHEV, the P510e, lists at £104,000. The Cayenne E-Hybrid Coupé tips past £100,000. For that money you get a car that can do short electric-only runs, which is worth remembering if you regularly drive in a Clean Air Zone or want to keep fuel costs down on predictable daily commutes. Both qualify for a zero-emission miles benefit in kind calculation, which is relevant if you are running either as a company car.

    On British roads: how they actually drive

    The Cayenne is the driver’s car. Full stop. Porsche’s adaptive air suspension reads the road better than anything else at this price point, and the steering has genuine weight and feedback that the Sport simply cannot match. On an A-road through the Peak District, the Cayenne feels like it belongs there. It is taut, committed, and communicative in a way that is unusual for a 2.2-tonne SUV.

    The Range Rover Sport handles our roads differently. Over genuinely rough tarmac, the pot-holed B-roads that the RAC flags in its annual reports as among the worst in Europe, the Sport’s air suspension simply absorbs more. It floats where the Cayenne occasionally thuds. I’d argue that for most UK buyers, who spend the majority of their miles on degraded tarmac rather than smooth alpine passes, that compliance is more valuable than outright chassis agility. If pothole damage is something you worry about, the Sport’s softer tune is a genuine practical advantage.

    Motorway cruising gives the Sport the edge too. Wind noise is lower, the seats are more cosseting over distance, and the cabin quiet at 70 mph is noticeably superior. For a car that will rack up a lot of miles on the M40 or M6, that matters.

    Premium SUV interior dashboard comparison relevant to Range Rover Sport vs Porsche Cayenne
    Photo by Vitali Adutskevich on Pexels

    Reliability reputation: the honest picture

    This is where the conversation gets uncomfortable for Land Rover fans. The brand’s reliability reputation has improved, but it carries baggage. Which? and JD Power UK surveys consistently place Jaguar Land Rover products below the industry average for ownership satisfaction, with electrical gremlins and infotainment software issues cited most frequently. The current Sport generation, which launched in 2022, has seen fewer catastrophic failures than its predecessor, but forum communities report persistent minor faults.

    Porsche is a different story. The Cayenne sits near the top of owner satisfaction surveys year after year. The mechanical architecture is shared with Volkswagen Group siblings, which means a deep UK dealer network and parts availability that is genuinely good. I spoke to a service advisor at a Porsche Centre in Birmingham who told me the most common Cayenne job they see is brake disc replacement, which is a testament to how few warranty issues they actually process.

    If reliability matters more than prestige badge cachet, the Cayenne wins this category clearly.

    Depreciation and total cost of ownership

    The Sport depreciates faster. That is a well-established pattern in UK car markets. CAP HPI data consistently shows Range Rover products retaining around 45 to 50 per cent of their new price after three years, while the Cayenne holds closer to 55 to 60 per cent. On a £95,000 car, that gap is worth roughly £9,000 to £14,000 over a standard three-year ownership period.

    There is a flip side. Because the Sport depreciates harder, buying one used at two to three years old is exceptional value. You can buy a nearly-new Sport for £50,000 to £60,000 that was pushing £90,000 new. If you are considering that route, it is worth reading our take on why nearly new cars can be cheaper than new right now, because the same dynamics apply here at scale.

    Running costs beyond depreciation are roughly comparable. Both need premium fuel (or have PHEV variants that reduce fuel spend significantly), both sit in the top VED band, and both carry insurance group ratings in the high 40s to 50s. Servicing is where the Cayenne tends to be cheaper, because Porsche’s service intervals are longer and dealer labour rates, whilst high, are usually below what a main Land Rover dealer charges.

    For buyers who want genuine off-road ability and might use their car for towing a caravan or a boat trailer, it is worth noting that both are accomplished tow vehicles. The Sport has a maximum towing capacity of 3,500 kg, matching the Cayenne exactly. Our broader look at the best tow cars in the UK covers the segment below these two, but the principles around nose weight and stability control apply equally here.

    The school run and daily life

    Both are genuinely practical family cars. Boot space in the Sport is 780 litres with the rear seats up; the Cayenne manages 770 litres in standard body form, rising to 857 litres in the Cayenne Sport Turismo estate variant if you need the extra room. Interior quality is close, though the Cayenne’s dashboard layout is cleaner and its infotainment system more intuitive. The Sport’s curved display looks dramatic but takes longer to learn.

    In terms of interior space, both accommodate three children across the back without real complaint, and both have ISOFIX points on the outer rear seats. The Sport’s higher seating position gives better visibility for parking in the tight spaces that come with urban school gates, which is a minor but real-world point.

    For anyone interested in how parts availability and ownership cost plays out in the broader SUV world, the community at Mitzybitz.com gives a useful sense of how older premium 4x4s hold up when you start looking at long-term maintenance realities.

    Which one should you buy?

    If you want the better driver’s car, with stronger reliability and less painful depreciation, the Cayenne is the rational choice. Porsche has earned its reputation for getting this formula right, and the 2026 Cayenne is the most complete version yet.

    If the badge matters, if you do occasional light off-roading, or if ride comfort on genuinely poor tarmac is your priority, the Range Rover Sport still earns its place. It is a more distinctly British luxury object, and there are worse things to be. Just go in clear-eyed about what the ownership experience might involve, and factor the depreciation curve into your finance calculation from the start.

    The DVLA’s VED rate tables are worth checking before you commit to either, because both sit in the highest road tax band and the PHEV exemption rules have changed for 2026 registrations.

  • What Is ULEZ and Clean Air Zone Charging in 2026? A Plain-English Guide for UK Drivers

    What Is ULEZ and Clean Air Zone Charging in 2026? A Plain-English Guide for UK Drivers

    If you’ve driven anywhere near a city centre recently, the chances are ULEZ and Clean Air Zones have crossed your mind. Either you’ve already paid a charge, or you’re quietly wondering whether your car is compliant. Either way, the network of charging zones across the UK has expanded considerably, and understanding exactly where you stand has become genuinely important for anyone who drives regularly. This guide covers what’s changed, what it costs, and how to check your vehicle before you get an unexpected fine through the letterbox.

    London road with ULEZ signage showing ULEZ and Clean Air Zones in operation
    Photo by Sarah O'Shea on Pexels

    What is ULEZ and how does it work?

    ULEZ stands for Ultra Low Emission Zone. London’s version, run by Transport for London, is the most prominent in the UK and currently covers the entire Greater London area, a boundary stretching out to the M25 in some directions. It operates 24 hours a day, every day of the year including bank holidays and Christmas Day. If your vehicle doesn’t meet the required emission standards and you drive within the zone, you pay a daily charge of £12.50 for cars, motorcycles and vans up to 3.5 tonnes. Larger vehicles such as heavier lorries and coaches pay £100 per day.

    The standards themselves are what trip most people up. For petrol cars, you need to meet Euro 4, which broadly means any petrol car first registered after January 2006. Diesel cars need to meet Euro 6, meaning they generally need to have been registered after September 2015. If your car is older than those cut-offs, it almost certainly doesn’t comply. Diesel vehicles are penalised harder here because Euro 6 is a significantly higher bar than Euro 4, which catches a lot of diesel drivers who assumed their car was fine.

    Clean Air Zones outside London: Birmingham, Bristol, Bradford and others

    The ULEZ conversation tends to dominate the headlines, but the network of Clean Air Zones (CAZs) across England is growing and, in some respects, more complicated because each city sets its own rules and charges independently.

    Birmingham runs a Class D Clean Air Zone, the most stringent category, which affects cars, taxis, vans, HGVs and buses. Non-compliant cars pay £9 per day. Birmingham’s zone covers the city centre and some surrounding areas. The West Midlands Combined Authority has a checker tool on its website where you can enter your number plate and get an immediate answer.

    Bristol took a different approach. Its CAZ launched targeting taxis, private hire vehicles, HGVs and buses rather than private cars, meaning most private motorists driving through Bristol aren’t currently charged. That said, the situation has evolved and it’s worth checking the current status directly with Bristol City Council before assuming you’re exempt.

    Bradford has been working towards its own CAZ for some time. The zone there focuses on taxis and light goods vehicles. As of 2026, private cars are not charged in Bradford’s zone, but commercial vehicle operators need to pay close attention.

    Bath operates a Class C zone. Non-compliant taxis, private hire vehicles, vans and larger vehicles are charged, but again private cars currently fall outside the direct charging scope there.

    The government’s clean air zone framework is coordinated through the Joint Air Quality Unit (JAQU), a partnership between the Department for Transport and DEFRA. You can use the national gov.uk Clean Air Zone checker to see every active zone in England and check vehicle compliance.

    ANPR camera above a UK road used to enforce ULEZ and Clean Air Zones charges
    Photo by AMORIE SAM on Pexels

    How to check if your car is ULEZ or CAZ compliant

    The quickest method is the TfL vehicle checker for London’s ULEZ, or the national CAZ checker on gov.uk. Both require just your number plate. Within seconds you’ll get a yes or no. I’d strongly recommend doing this before any city trip rather than relying on assumptions about your car’s age, plenty of drivers have been caught out because they didn’t realise their diesel was registered just a few months before the Euro 6 cut-off date.

    If you want to go deeper on your specific vehicle’s emission category, engine type and first registration date, tools like Car Data Wiki can help you dig into the technical specification of a particular model, useful if you’re buying a used car and want to confirm compliance before committing.

    It’s also worth knowing that the DVLA’s V5C logbook lists the Euro emission standard on many vehicles registered after 2001. Check box V.7 on your V5C. If it’s blank or unclear, use the online checkers rather than guessing.

    What exemptions exist for ULEZ and Clean Air Zones?

    Several categories of vehicle are exempt from ULEZ charges in London. Military vehicles, vehicles used by disabled people who receive certain benefits, historic vehicles registered before 1 January 1979, and vehicles with a ‘disabled’ or ‘disabled passenger vehicles’ tax class are all exempt. There are also temporary exemptions available in some circumstances, though these have been narrowed considerably since the zone expanded.

    London’s scrappage scheme has now ended for most applicants, though it ran for several years and helped lower-income Londoners replace non-compliant vehicles. If you’re currently stuck with a non-compliant car and driving frequently in London, the maths of paying £12.50 daily adds up fast, roughly £4,562 per year if you drive in seven days a week. At that rate, replacing the vehicle becomes the only sensible long-term option.

    For the national CAZ network, exemptions vary by city. Generally, zero-emission electric vehicles are exempt everywhere. Many zones also exempt vehicles that are retrofitted with approved clean air technology, particularly for taxis and vans. Check each city’s specific exemption list rather than assuming London’s rules apply universally.

    What happens if you don’t pay?

    In London, TfL’s cameras read number plates automatically. If your vehicle is non-compliant and detected inside the ULEZ boundary, you’ll receive a Penalty Charge Notice. The fine is £160, reduced to £80 if paid within 14 days. TfL processed millions of these PCNs in 2024 and 2025, so the idea that enforcement is patchy simply isn’t supported by the evidence.

    For CAZs in other cities, the enforcement mechanism is similar, automatic number plate recognition (ANPR) cameras, followed by a postal fine. Charges for non-payment are typically double the daily rate.

    What this means if you’re buying a used car right now

    The compliance question has become a real factor in used car values. Non-compliant diesels registered before 2015 have taken a significant hit in resale value, particularly in cities. If you’re shopping for a used car, checking ULEZ and CAZ compliance before you buy is as important as checking the service history. I’d go so far as to say a car that fails both London’s ULEZ and Birmingham’s CAZ is essentially unsellable to anyone who lives or works in either city.

    This connects to the broader picture of the real cost of keeping an older petrol or diesel car in the UK as emissions regulations tighten. And if you’re considering switching to electric specifically to avoid these charges, it’s worth reading up on whether leasing or buying makes more financial sense before committing. The compliance issue also feeds into the resale dynamics that explain why some nearly new cars are selling for less than their new equivalents right now.

    The short version: if you drive in or near any major UK city and your vehicle is more than a decade old, take ten minutes to check your plate on gov.uk’s CAZ checker. The fine for not doing so is considerably more than ten minutes of your time.

  • UK Driving Licence Categories Explained: What You Can and Cannot Drive in 2026

    UK Driving Licence Categories Explained: What You Can and Cannot Drive in 2026

    Most people pass their test, shove the photocard licence in a drawer and never look at it again. Then one day they want to hire a motorhome, tow a heavier trailer, or ride a motorbike, and suddenly all those codes on the back of the card mean something. With the DVLA’s rules sitting behind quite a few recent changes, I thought a proper, accurate breakdown was overdue. Here is every major driving licence category on a UK photocard licence, what each one permits, and where age or medical rules change things.

    UK driving licence categories explained 2026 - photocard showing entitlement codes on the back
    Photo by Lisa Fotios on Pexels

    What the codes on your photocard licence actually mean

    Your photocard has two sides. The front has your photo and personal details; the back lists entitlement codes in columns showing the category, start date, expiry, and any restriction codes. The categories are set by DVLA under legislation derived from EU directives, which the UK retained post-Brexit. You can check or share your licence details at any time through GOV.UK’s View Driving Licence service, which is worth doing before any vehicle hire or employment check.

    Category B: the one almost everyone has

    Category B is the standard car licence. It covers vehicles up to 3,500 kg maximum authorised mass (MAM) with no more than eight passenger seats, plus a trailer up to 750 kg. Pass your test and you get category B automatically at age 17. One thing people regularly miss: if you passed your test in an automatic, your licence carries a restriction code (code 78) limiting you to automatic transmission vehicles. You cannot legally drive a manual car until you pass a further test in one. That restriction matters more than ever now that a lot of fleet and rental cars still have manual gearboxes, and it can catch people out when they book a hire car abroad or need a van at short notice.

    Category B also gives you provisional entitlement to tow a trailer between 750 kg and 3,500 kg (combined MAM not exceeding 3,500 kg), but anything heavier requires the BE category. If you passed your test before 1 January 1997, you probably already have BE and C1 on your licence as acquired rights.

    Category BE: towing heavier trailers

    BE covers a category B vehicle towing a trailer over 750 kg where the combined weight of vehicle and trailer exceeds 3,500 kg. You need to pass a separate towing test to get this. The practical test involves coupling and uncoupling, and an off-road reversing exercise. Anyone serious about caravanning with a heavy twin-axle or towing a car on a trailer should check whether their licence actually includes BE rather than assuming it does. If you’re researching tow cars and wondering what legal weight limits apply to you, it’s worth reading alongside a piece on the best tow cars in the UK for 2026 to understand how vehicle rating connects to your licence category.

    Category B1: light quadricycles

    B1 covers light quadricycles, think Renault Twizy-style vehicles with a maximum unladen mass of 400 kg (550 kg for goods vehicles) and a top speed not exceeding 45 mph. In practice, B1 is usually acquired automatically alongside a full B licence. It is occasionally relevant for people looking at micro EVs or specialised mobility vehicles, but most UK drivers will never need to think about it separately.

    Category AM: mopeds and small scooters

    AM covers two or three-wheeled vehicles with a maximum design speed between 25 km/h and 45 km/h, and light four-wheeled vehicles under the B1 threshold. The minimum age is 16. Anyone with a full car licence issued after 1 February 2001 gets provisional AM entitlement, but you still need to complete Compulsory Basic Training (CBT), pass theory and practical tests to get full AM. CBT alone lets you ride a moped on L-plates.

    Category A: motorcycles

    This is where it gets more layered. There are three routes depending on age and experience.

    • A1: motorcycles up to 125 cc and 11 kW, from age 17.
    • A2: motorcycles up to 35 kW with a power-to-weight ratio not exceeding 0.2 kW/kg, from age 19. You can access A2 direct, or via A1 after two years.
    • A (full): unrestricted. From age 24 direct, or from age 21 after holding A2 for two years. The progressive access route at 21 is worth knowing if you’re keen to get on a litre bike sooner.

    All motorcycle categories require CBT, theory, and module one and two practical tests at each stage.

    Categories C, C1, CE and C1E: lorries and larger goods vehicles

    C1 covers goods vehicles between 3,500 kg and 7,500 kg MAM. It’s the category you need for a larger motorhome or a big horsebox that exceeds the 3,500 kg B limit. Minimum age is 18. C covers any goods vehicle over 3,500 kg (full lorry territory), also from 18, and requires a Driver Certificate of Professional Competence (CPC) for commercial use. CE and C1E add trailer entitlements to the respective categories. Drivers doing commercial goods work need periodic CPC training, currently 35 hours every five years.

    Categories D, D1, DE and D1E: passenger-carrying vehicles

    D1 allows you to drive minibuses with between 9 and 16 passenger seats, for a distance not exceeding 50 km from the point of departure, without payment. This is the one that catches community minibus drivers, school run operators and sports clubs out. D is the full bus and coach category. Minimum age for both is 21, though 18 is possible in some circumstances for D. D1E and DE add trailer entitlements. Commercial drivers again need CPC.

    Restriction codes: what those numbers alongside your category mean

    The columns next to each category on your licence often contain numeric restriction codes. Common ones to know:

    • 01: corrective lenses (you must wear glasses or contacts when driving)
    • 78: automatic transmission only
    • 96: towing with category B where combined weight is between 3,500 kg and 4,250 kg (a specific acquired right for some)
    • 101: not for hire or reward
    • 119: weight, power or speed restriction

    These codes matter legally. Driving outside a restriction is the same as driving without a licence for that vehicle type, which has insurance implications too.

    How medical conditions and age affect your entitlements

    Standard category B licences are issued until age 70, then renewed every three years. Group 2 licences (C and D categories) require more rigorous medical standards and are renewed more frequently. Conditions including epilepsy, diabetes treated with insulin, certain heart conditions and vision problems all have specific DVLA notification requirements. Failing to notify DVLA of a relevant medical condition can invalidate your insurance and result in a fine of up to £1,000. The DVLA publishes detailed guidance on medical standards for driving, and your GP or specialist can advise whether your condition requires notification.

    Age rules interact with licences in another practical way: if you’re looking at a used car purchase and comparing running costs across different vehicle types, understanding which categories your licence covers will shape what you can legally drive on day one. For context on how those running costs stack up more broadly, the breakdown on the real cost of keeping a petrol car beyond 2030 is useful reading alongside the licence picture, particularly if you’re planning ahead for a category C1 motorhome or heavier vehicle that may be affected by future emission charges.

    Checking and updating your entitlements

    If you think you might have acquired rights from an older licence, or you’ve done additional tests and the new category hasn’t appeared yet, check via the GOV.UK service or contact DVLA directly. Acquired rights from pre-1997 licences can include C1, D1, and others that newer drivers have to test for. It’s also worth checking your licence before any vehicle subscription, lease or hire arrangement, since many operators now do digital DVLA checks. For those weighing up whether a lease or outright purchase makes more sense for a vehicle that needs a specific category, the comparison of leasing vs buying a car in the UK in 2026 covers some of the practical considerations that overlap with licence entitlement and eligibility checks.

    The codes on the back of your photocard aren’t just administrative filler. They define what you’re legally allowed to drive, under what conditions, and with what restrictions. Getting it wrong isn’t a paperwork issue, it’s an insurance and legal one. Five minutes checking your entitlements properly is time well spent.

    Frequently Asked Questions

    What vehicles can I drive with a standard category B UK licence?

    Category B covers cars and light vans up to 3,500 kg MAM with no more than eight passenger seats, plus a trailer up to 750 kg. If you passed your test in an automatic, a code 78 restriction means you can only drive automatic vehicles unless you pass a further manual test.

    Do I need a special licence to tow a caravan in the UK?

    It depends on the combined weight. If your car plus the caravan exceeds 3,500 kg MAM, you need category BE on your licence, which requires a separate towing test. Drivers who passed their test before 1 January 1997 usually have BE as an acquired right already.

    What is the minimum age to ride a motorbike in the UK?

    You can complete CBT and ride a moped (AM category) at 16. Category A1 motorcycles up to 125 cc are available from 17. The full A category (unrestricted bikes) requires you to be at least 24, or 21 if you’ve held an A2 licence for two years.

    What does restriction code 78 mean on a UK driving licence?

    Code 78 means you are restricted to vehicles with automatic transmission only. It’s added to your licence if you passed your practical driving test in an automatic car. To have it removed, you must pass a further test in a manual vehicle.

  • Peugeot E-3008 Long-Term Review: What Six Months of Real UK Ownership Actually Reveals

    Peugeot E-3008 Long-Term Review: What Six Months of Real UK Ownership Actually Reveals

    The Peugeot E-3008 arrived with a lot of promise and, to Peugeot’s credit, a genuinely striking interior that made plenty of rivals look dated. I’ve been running one on UK roads for six months now, racking up just under 7,000 miles in the process, and the picture that’s emerged is more complicated than the launch-event enthusiasm suggested. This Peugeot E-3008 long term review UK covers the stuff that matters after the honeymoon period: what the range is actually like on the motorway, how the public charging network treats you, whether the software holds up, and what the car is worth in the current market if you need to sell.

    Peugeot E-3008 electric SUV on a UK road during long term ownership review
    Photo by Denys Gromov on Pexels

    Real-world range on UK roads

    Peugeot claims up to 435 miles of WLTP range for the Long Range single-motor variant. In practice, on a mixed run of A-roads and dual carriageways at the speeds British roads demand, I’ve consistently landed between 270 and 310 miles on a full charge. Drop onto the motorway at a steady 70mph and that figure slides closer to 240 miles. It’s not disastrous by current electric car standards, but it’s a meaningful gap from the official figure, and one you should budget for before committing to a long trip.

    In warmer weather, the range recovered noticeably. A run from Manchester to Leeds and back on a mild April morning yielded around 3.8 miles per kWh, which is respectable for a car of this size and weight (just over 1,900kg). Winter is where things tighten up; a January run to Birmingham and back used noticeably more energy than the on-board computer had predicted, largely because heated seats, the heated steering wheel and the cabin heater were all working hard. If you’re buying one of these as your only car for year-round British use, factor in roughly 20 to 25 per cent less range from November through February.

    Charging on the British public network

    This is where I have the most to say, and not all of it is flattering to the wider infrastructure rather than the car itself. The E-3008 supports charging at up to 160kW DC, which sounds competitive. Getting it to actually hit that rate on real UK chargers is another matter. Gridserve’s Electric Highway network gave me the most consistent rapid charges, with several sessions at 130 to 145kW at services on the M6 corridor. BP Pulse was patchier; I had two sessions abort within the first minute, requiring me to unplug, reposition and try again.

    On the car’s side, the charging curve does drop off reasonably early. I measured a noticeable throttling around the 60 per cent state of charge point during several motorway charging stops, which means the 10 to 80 per cent charge target takes roughly 35 to 40 minutes when the charger is cooperating. Peugeot quotes 30 minutes; in my experience that’s optimistic outside of ideal conditions. The on-board navigation’s charge planning is competent enough to route you via chargers, but I’d still recommend cross-referencing with Zap-Map before a long run, particularly on less-travelled routes in Wales or the Scottish Borders where fast charger density remains thin.

    Home charging via a 7.4kW wallbox is painless. Overnight from around 20 per cent to full takes approximately seven hours, which fits neatly into an economy tariff overnight window. If you’re primarily doing a commute and charging at home, the public network frustrations become far less relevant.

    Software reliability: the honest picture

    Peugeot’s Panoramic i-Cockpit is genuinely one of the best-looking dashboards in any car at this price point. The panoramic curved display is crisp, the layout is logical, and the physical toggle controls for the climate system are a genuine relief compared to rivals that bury everything in menus. That said, it hasn’t been without issues over six months.

    I’ve had two instances where the infotainment system lost its Bluetooth connection entirely and required a full reboot. On one occasion the rearview camera feed froze mid-manoeuvre, which was more alarming than dangerous but still unsettling. A software update delivered over-the-air in March resolved what appeared to be the Bluetooth issue, and it hasn’t recurred since. The navigation system’s traffic data is occasionally behind what Google Maps would tell you, so I tend to run a phone mount alongside it on longer journeys.

    One recurring minor irritant: the driver assistance systems reset to their default (more intrusive) settings on every ignition cycle. The lane-keeping assist, in particular, is set to intervene quite aggressively by default, and having to dial it back every single time you get in the car after a fortnight of ownership gets old quickly. It’s a fixable software behaviour; Peugeot should sort it out.

    What depreciation looks like right now

    The UK used car market for electric vehicles has been turbulent, and the E-3008 isn’t immune. I’ve been tracking equivalent examples on Auto Trader and Motorpoint over the past few months. A six-month-old E-3008 Allure Long Range, which originally listed at around £47,000, is currently appearing at between £36,000 and £39,000 on the used market. That’s a depreciation hit of roughly 17 to 23 per cent in six months, which is steeper than the equivalent combustion SUV in the same segment but broadly in line with where most electric cars are landing right now.

    The phenomenon of nearly-new electric cars appearing cheaper than list price is very much alive here. If you’re open to buying a pre-registered or short-lease-return E-3008 rather than new, the saving is substantial. For buyers already wrestling with whether to lease or buy in the current market, the depreciation picture makes a lease argument slightly more compelling for this particular car, given how much equity can evaporate in the first year of ownership.

    The government’s current Benefit in Kind rates for zero-emission company cars remain very favourable at 3 per cent for the 2025/26 tax year, according to HMRC’s published rates. That makes the E-3008 a genuinely strong option if you’re running it as a company car and the depreciation is someone else’s problem.

    Build quality and living with it day to day

    Six months in, the interior quality has held up well. There’s no rattling trim, no creaking dashboards, and the seat bolsters haven’t shown any premature wear despite regular use. Boot space at 520 litres is genuinely practical. The driving position, thanks to that high seating stance and the raised instrument binnacle, took me a few weeks to fully get used to, but I’d now say I find it natural. Ride quality on UK B-roads is composed without being wallowy, though larger potholes do occasionally find their way through in a manner that makes me grateful for the growing awareness around pothole damage compensation.

    The E-3008 is a genuinely good electric SUV. It looks the part, drives well, and the interior is leagues ahead of many competitors at the price. The charging network’s inconsistency is a British infrastructure problem as much as a Peugeot one, and the real-world range, while short of WLTP claims, isn’t unusual for the class. The software niggles are annoying but not deal-breaking. Whether it’s the right car for you depends heavily on how much of your charging you can do at home, and whether you can absorb the depreciation curve that’s currently baked into any new electric SUV purchase.

  • The Real Cost of Keeping a Petrol Car Beyond 2030 in the UK: Tax, Resale Value and Running Costs Explained

    The Real Cost of Keeping a Petrol Car Beyond 2030 in the UK: Tax, Resale Value and Running Costs Explained

    A lot of drivers I speak to have quietly made the same decision: keep the petrol car, see what happens, and deal with the consequences later. It’s a reasonable instinct. The car is paid off, it runs fine, and the thought of committing to an EV on a charging network that still has reliability issues feels premature. But “deal with the consequences later” is arriving faster than most people planned for, and the financial picture is more complicated than simply paying for fuel and an annual service. Understanding the genuine cost of keeping a petrol car UK 2030 and beyond means looking at several converging pressures at once.

    Petrol car at a UK filling station illustrating the cost of keeping a petrol car UK 2030
    Photo by Engin Akyurt on Pexels

    VED: what the tax changes actually look like for older petrol and diesel cars

    Vehicle Excise Duty has already started to shift against internal combustion engine vehicles. From April 2025, new electric cars were brought into standard VED rates for the first time, which sounds like levelling the playing field. In practice, though, the government’s longer-term trajectory continues to favour zero-emission vehicles. The current VED rate tables on GOV.UK show that cars registered after April 2017 pay a flat standard rate, but older petrol cars registered before that date are taxed on CO2 emissions, and those bands have not shrunk over time.

    What’s coming after 2030 is the sharper issue. Once the new petrol car sale ban comes into effect, HMRC and the Treasury will need to replace fuel duty revenue from somewhere. Fuel duty currently raises around £25 billion per year, and as the fleet electrifies, that income disappears. Road pricing, higher VED for combustion vehicles, or supplementary levies on petrol and diesel use are all credible policy directions. No firm legislation exists yet, but the direction of travel is clear: retaining an older ICE car will become progressively more expensive from a tax standpoint, not less.

    Residual values: the slow collapse nobody is planning for

    This is the one that I think genuinely catches people off guard. Residual values for petrol and diesel cars have held up better than many EV advocates predicted over the past two years, partly because EV residuals themselves dropped sharply. But that equilibrium will not last indefinitely.

    Once the 2035 petrol sale ban milestone approaches, the second-hand market for older combustion cars faces a structural problem: a very large supply of vehicles that cannot legally be sold new, competing for buyers who are increasingly accustomed to electric running costs. Cap HPI and Cazana both track UK used car valuations closely, and their projections consistently show petrol cars registered between 2020 and 2030 losing value faster than equivalent models did in previous decades once they pass the ten-year mark.

    A petrol car you buy new today for £28,000 might be worth £8,000-£10,000 by 2035 under a moderate depreciation scenario. Under a pessimistic one, where EV adoption accelerates rapidly and petrol demand compresses, the same car could be worth considerably less. I’d argue most private owners are not pricing this into their decision-making at all, because the loss is invisible until the day they try to sell or part-exchange.

    This also has knock-on effects for anyone who bought using personal contract purchase (PCP). If the guaranteed minimum future value set at the start of the agreement proves optimistic, you face a gap finance situation that leaves you with negative equity. Anyone considering PCP on a petrol car right now should read our detailed comparison of leasing versus buying before committing, because the residual value assumptions baked into those deals will look very different by the early 2030s.

    Servicing and parts availability after the mandate kicks in

    Combustion engine servicing is not going away overnight. Independent garages will continue to service petrol and diesel cars for decades, and main dealers have a commercial incentive to retain older vehicles as servicing revenue while new car sales shrink. The Society of Motor Manufacturers and Traders (SMMT) estimates there are currently around 40 million vehicles on UK roads, and the majority are still petrol or diesel. That fleet does not vanish in 2030.

    What does change is the economics of parts. Once manufacturers stop producing new ICE platforms, economies of scale for replacement components begin to shrink. This is already visible in the used car market for models that were discontinued early. Specialist parts for older diesel engines, catalytic converters, particulate filters and increasingly complex emissions-control systems all carry a premium. As more workshops pivot their training and tooling towards EVs, finding a technician who genuinely understands a complex turbocharged petrol engine may become less straightforward in some parts of the country.

    Broadly, I’d estimate that routine servicing costs for a petrol car held past 2032 will rise by somewhere between 15% and 25% in real terms, driven by parts costs rather than labour rates. For high-mileage drivers, that adds up quickly.

    How lenders are already changing the way they view older ICE vehicles

    This is the most immediate financial pressure, and it is already happening. Several UK lenders have quietly started to apply higher interest rates to finance agreements on older petrol and diesel cars, particularly those with higher emissions. The logic is straightforward: the collateral backing the loan is depreciating faster than historical models predicted, so the lender’s risk is higher.

    Equity release and secured loan products that use your car as an asset are also being reassessed. A diesel SUV that was worth £22,000 two years ago and is now worth £16,000 represents a meaningfully different risk profile to a lender than it did previously. This is worth keeping in mind if you are considering using a petrol vehicle as a trade-in or part of a broader finance arrangement, as the valuation offered by the lender may be lower than any online estimate you find.

    For context on how the ZEV mandate is already reshaping the choices available to buyers and dealers alike, our piece on what the ZEV mandate means in practice covers the regulatory mechanics in detail. The short version: manufacturers are under real pressure now, not in 2030, and that pressure is already filtering down into pricing and availability of ICE models.

    Is holding onto your current petrol car actually worth it?

    Honestly, it depends almost entirely on your mileage, your ownership timeline and whether you finance the vehicle or own it outright. For cash buyers who drive modest mileages and plan to run a car for ten or more years regardless of its resale value, a well-maintained petrol car bought today or held from an existing purchase can still make financial sense. Running costs per mile remain competitive, particularly for drivers who spend most of their time on motorways rather than in city traffic where hybrids and EVs have their biggest advantage.

    The calculation looks worse for higher-mileage drivers, anyone using finance, and anyone who lives in or near a city that is actively expanding clean air zones. It also looks worse if you drive a diesel, where residual value collapse is already more pronounced and regulatory pressure is heavier. The 2035 petrol car ban is the end point, but the financial effects of the transition are front-loaded into the years before it.

    My take: if you are within two or three years of naturally replacing your car anyway, this is probably the moment to think carefully about your next move rather than assuming petrol will always be the safe default. The cost of keeping a petrol car in the UK past 2030 is not catastrophic for every owner, but it is real, it is measurable, and for most drivers it is going to be higher than they currently expect.

    Frequently Asked Questions

    Will VED (road tax) increase for petrol cars after 2030 in the UK?

    No firm legislation has been passed yet, but the government needs to replace fuel duty revenue as the fleet electrifies. Most independent analysts expect VED to rise for older petrol and diesel vehicles in the early 2030s, either through higher standard rates or new emissions-linked surcharges. Drivers should treat current rates as a floor rather than a ceiling.

    How much will my petrol car be worth in 2030 or 2035?

    Residual value projections from Cap HPI and Cazana suggest petrol cars registered between 2020 and 2030 will depreciate faster than previous generations once they pass the ten-year mark, partly due to competition from cheaper used EVs. A car worth £28,000 today could realistically be worth £8,000-£10,000 by 2035 under a moderate scenario, less under a pessimistic one.

    Will it become harder to get finance on an older petrol car?

    Yes, this is already beginning to happen. Some UK lenders are applying higher interest rates to finance agreements on older or high-emission ICE vehicles because the collateral depreciates faster than historical models predicted. Trade-in and part-exchange valuations offered by dealers may also reflect this more conservative risk assessment.

  • Leasing vs Buying a Car in the UK in 2026: Which Option Actually Saves You Money?

    Leasing vs Buying a Car in the UK in 2026: Which Option Actually Saves You Money?

    The question of car leasing vs buying UK 2026 style has never been more loaded. With interest rates still sitting higher than anyone would like, electric cars rapidly reshaping residual values, and manufacturers throwing increasingly tempting lease deals at conquest buyers, the numbers genuinely shift depending on which route you take. I’ve spent time crunching the figures across three common scenarios, using real asking prices and current finance rates, and the answer is never as clean as the showroom salesperson makes it sound.

    Car finance discussion at a UK showroom, relevant to car leasing vs buying UK 2026
    Photo by Dextar Studio ™ on Pexels

    The three main routes explained quickly

    Personal Contract Hire (PCH) is a straight lease. You pay a fixed monthly amount, hand the car back at the end, and never own it. Personal Contract Purchase (PCP) looks similar monthly but includes a large optional final payment (the guaranteed minimum future value, or GMFV) that lets you buy the car outright, swap into a new deal, or walk away. Outright purchase is exactly what it sounds like: you pay the full price, either in cash or via a personal loan, and the car is yours from day one.

    Each suits a different type of driver. The trick is knowing which type you actually are, not which type you think you are.

    Real numbers: a Volkswagen Golf on all three deals

    Take a 2026 Volkswagen Golf 1.5 eTSI Style, on-the-road price roughly £33,500. I’ve used representative current market figures rather than headline teaser rates.

    PCH: A 36-month, 10,000 miles per year lease is currently available from around £289 per month (plus an initial rental of three months upfront, so roughly £867 day one). Total cost over three years: approximately £11,271 including the initial rental. You hand it back. You have nothing.

    PCP: Same term, same mileage. Monthly payment climbs to around £349 with a deposit of £3,500, giving a total paid before the balloon of approximately £15,064. The GMFV on a Golf over 36 months at that mileage sits at roughly £16,800. If you want to keep it, your total outlay hits nearly £32,000. If you walk away, you’ve paid £15,064 for three years of driving.

    Outright purchase (personal loan): With the average UK personal loan rate for £33,500 sitting around 7.9% APR over three years in 2026, monthly payments come to roughly £1,050. Total cost: approximately £37,800. You own a three-year-old Golf with roughly 30,000 miles on it, probably worth £16,500 to £18,000 at current used car values. Net cost of ownership after resale: around £20,000 to £21,000.

    How annual mileage changes everything

    This is where car leasing vs buying UK 2026 comparisons get genuinely interesting. If you cover 20,000 miles per year, PCH pricing changes dramatically. Excess mileage on most lease contracts runs at 6p to 12p per mile. On a 10,000-mile contract doing 20,000 miles, that’s an extra 10,000 miles at, say, 9p: £900 per year, or £2,700 over the term. Your effective PCH cost jumps to roughly £13,971, and the car still isn’t yours.

    A 20,000-mile PCP contract exists but the monthly payment rises and the GMFV drops (higher mileage depresses residuals). The balloon shrinks to maybe £13,500, meaning if you walk away your total outlay is similar, but the car is worth less if you had owned it. High-mileage drivers, generally above 15,000 miles per year, almost always come out better with outright ownership or a personal loan, precisely because they’re not paying mileage penalties and they benefit from running the car well beyond three years.

    Low-mileage drivers (under 8,000 miles per year) are the sweet spot for PCH. Lease rates fall, damage risk is lower, and handing back a barely-used car with no maintenance headaches makes genuine financial sense, particularly for urban drivers who only really need a car at weekends. If that sounds like you, nearly new cars are sometimes priced below new equivalents right now, which can make PCP on a lightly used model even sharper than a brand-new lease.

    The hidden costs people forget to factor in

    PCH and PCP both look cheaper until you account for gap insurance (typically £150 to £300 over the term on PCP), the fact that any fault or excessive wear beyond fair use costs you at return, and the reality that you are perpetually making payments with no equity building. Miss a payment on PCP and the finance house can repossess; your credit rating takes a hit that will affect every subsequent deal.

    Outright ownership has its own hidden costs: you carry the full depreciation risk, and electric cars have made this genuinely unpredictable. The used EV market has moved sharply in the last two years as the UK’s Zero Emission Vehicle mandate pushed more EVs onto forecourts, compressing residuals on some models. If you buy a battery electric vehicle outright and the market shifts again, you absorb that loss personally. Under PCH, the leasing company absorbs it.

    The RAC Foundation’s motor industry data consistently shows that finance deals now account for over 90% of new private car sales in the UK, which tells you most buyers have already decided against cash purchase, whether or not the numbers fully justify it.

    Which option suits which buyer?

    My honest read: PCH works best for drivers who want a new car every two to three years, cover under 12,000 miles annually, and genuinely do not want the hassle of ownership, servicing surprises, or resale negotiation. The monthly figure is the monthly figure; budget accordingly and it’s simple.

    PCP works for buyers who think they might want to keep the car but want the flexibility not to. The balloon payment effectively lets you decide in three years. The risk is that you start a new PCP off the back of an old one indefinitely, and a lot of people do exactly that, paying forever with nothing to show for it. If you’re eyeing something sporty, it’s worth reading how performance cars like the GR86 and MX-5 hold their values compared to mainstream models before committing to a GMFV figure on a PCP deal.

    Outright ownership wins on pure long-term cost, but only if you keep the car for five years or more. Buy right, maintain it properly, and the total cost of motoring over a decade comfortably undercuts serial leasing. The discipline required is actually keeping the car past the point where it starts to feel boring, which, in fairness, most of us struggle with.

    A quick note on electric cars and leasing specifically

    EVs complicate the car leasing vs buying UK 2026 picture considerably. Battery technology is advancing fast enough that a three-year-old EV can feel meaningfully outdated in range terms, which makes leasing electrics more logical than owning them for most drivers. The manufacturer absorbs the technology risk, you get a new battery chemistry every contract cycle, and servicing costs remain minimal throughout. It’s one of the few scenarios where PCH arguably has a structural advantage over ownership regardless of mileage.

    The bottom line is that there is no universally correct answer. Run the numbers for your specific mileage, your likelihood of actually keeping the car past the initial term, and your tolerance for risk on residual values. The showroom deal that feels cheapest on the monthly figure rarely is when you look at the total cost of the full term.

    Frequently Asked Questions

    Is it cheaper to lease or buy a car in the UK in 2026?

    It depends on how long you keep the car. Leasing (PCH) has lower monthly costs and no residual value risk, but you build no equity. Outright ownership is cheaper over five years or more, particularly if you buy well and avoid high-mileage penalties.

    What is the difference between PCP and PCH car finance?

    PCP (Personal Contract Purchase) gives you the option to buy the car at the end of the agreement via a balloon payment, whereas PCH (Personal Contract Hire) is a straight lease with no purchase option. PCP monthly payments are usually slightly higher than PCH because you’re financing a portion of the car’s value.

    How does annual mileage affect whether I should lease or buy?

    High-mileage drivers (above 15,000 miles per year) typically pay significant excess mileage charges on leases, making outright purchase or a personal loan more cost-effective. Low-mileage drivers under 10,000 miles per year usually get the best lease rates and face fewer penalties at return.

    Can I negotiate the mileage limit on a car lease in the UK?

    Yes, most leasing companies will quote across different annual mileage bands from 6,000 to 30,000 miles. Setting a higher mileage limit upfront is always cheaper per mile than paying excess mileage charges at the end of the contract, so estimate conservatively and build in a buffer.